Buy bilanzierung.eu ?
We are moving the project
bilanzierung.eu .
Are you interested in purchasing the domain
bilanzierung.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy bilanzierung.eu ?
What are deductible expenses for a house?
Deductible expenses for a house typically include mortgage interest, property taxes, and mortgage insurance premiums. Additionally, expenses related to home office use, certain home improvements for medical purposes, and energy-efficient home upgrades may also be deductible. It's important to keep detailed records and consult with a tax professional to ensure you are correctly identifying and claiming all eligible deductions for your home. **
What expenses do I have after buying a house?
After buying a house, you will have ongoing expenses such as property taxes, homeowner's insurance, and possibly private mortgage insurance (PMI) if you put down less than 20% as a down payment. You will also have to budget for maintenance and repairs, as well as utilities such as water, electricity, and gas. Additionally, if you have a mortgage, you will have monthly mortgage payments that include principal and interest. It's important to budget for these expenses to ensure you can comfortably afford homeownership. **
Similar search terms for Thorsons-Cornerstone-Harriman-House
Top-Angebote
Products related to Thorsons-Cornerstone-Harriman-House:
-
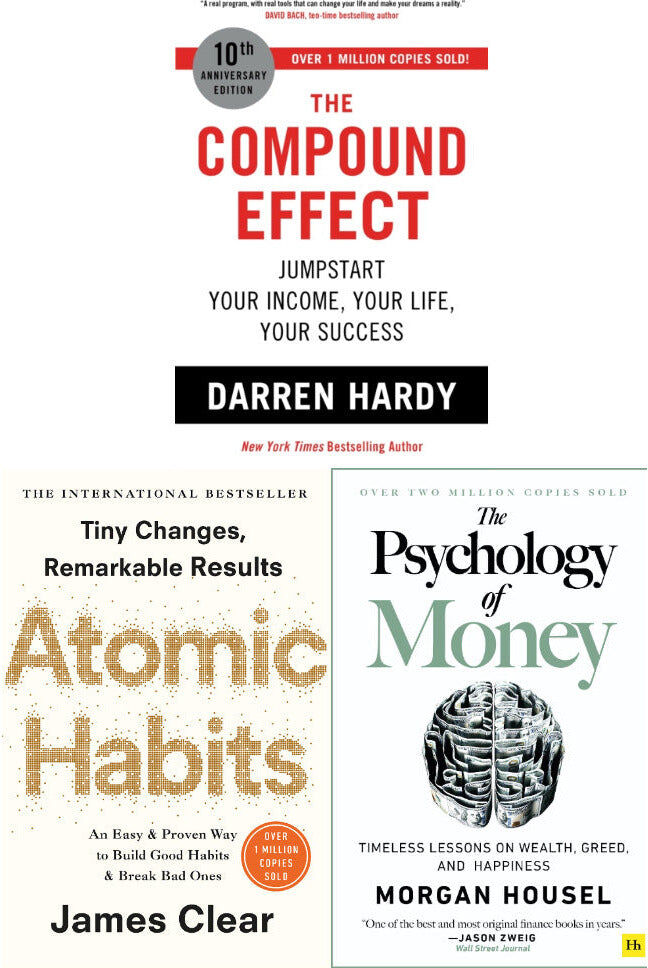
Harriman House Atomic Habits, The Compound Effect, The Psychology of Money 3 Books Collection SetAtomic Habits People think that when you want to change your life, you need to think big. But world-renowned habits expert James Clear has discovered another way. He knows that real change comes from the compound effect of hundreds of small decisions: doing two push-ups a day, waking up five minutes early, or holding a single short phone call. The Compound Effect As the central curator of the success media industry for over 25 years, author Darren Hardy has heard it all, seen it all, and tried most of it. This book reveals the core principles that drive success. The Compound Effect contains the essence of what every superachiever needs to know, practice, and master to obtain extraordinary success. Inside you will find strategies on: How to win--every time! The Psychology of Money Doing well with money isn't necessarily about what you know. It's about how you behave. And behavior is hard to teach, even to really smart people. Money investing, personal finance, and business decisions is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet.22,95 £*Shipping: 2,99 £Secure redirect to the provider
-
Random House Business/Harriman House ltd Atomic Habits & The Psychology of Money – 2 Books Collection Set Personal Growth, Wealth & Mindset BestsellersAtomic Habits People think that when you want to change your life, you need to think big. But world-renowned habits expert James Clear has discovered another way. He knows that real change comes from the compound effect of hundreds of small decisions: doing two push-ups a day, waking up five minutes early, or holding a single short phone call. He calls them atomic habits. In this ground-breaking book, Clears reveals exactly how these minuscule changes can grow into such life-altering outcomes. He uncovers a handful of simple life hacks (the forgotten art of Habit Stacking, the unexpected power of the Two Minute Rule, or the trick to entering the Goldilocks Zone), and delves into cutting-edge psychology and neuroscience to explain why they matter. Along the way, he tells inspiring stories of Olympic gold medalists, leading CEOs, and distinguished scientists who have used the science of tiny habits to stay productive, motivated, and happy. The Psychology of Money Doing well with money isn't necessarily about what you know. It's about how you behave. And behaviour is hard to teach, even to really smart people. Money investing, personal finance, and business decisions is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet. They make them at the dinner table, or in a meeting room, where personal history, your own unique view of the world, ego, pride, marketing, and odd incentives are scrambled together. In The Psychology of Money, award-winning author Morgan Housel shares 19 short stories exploring the strange ways people think about money and teaches you how to make better sense of one of life's most important topics.15,99 £*Shipping: 2,99 £Secure redirect to the provider
-
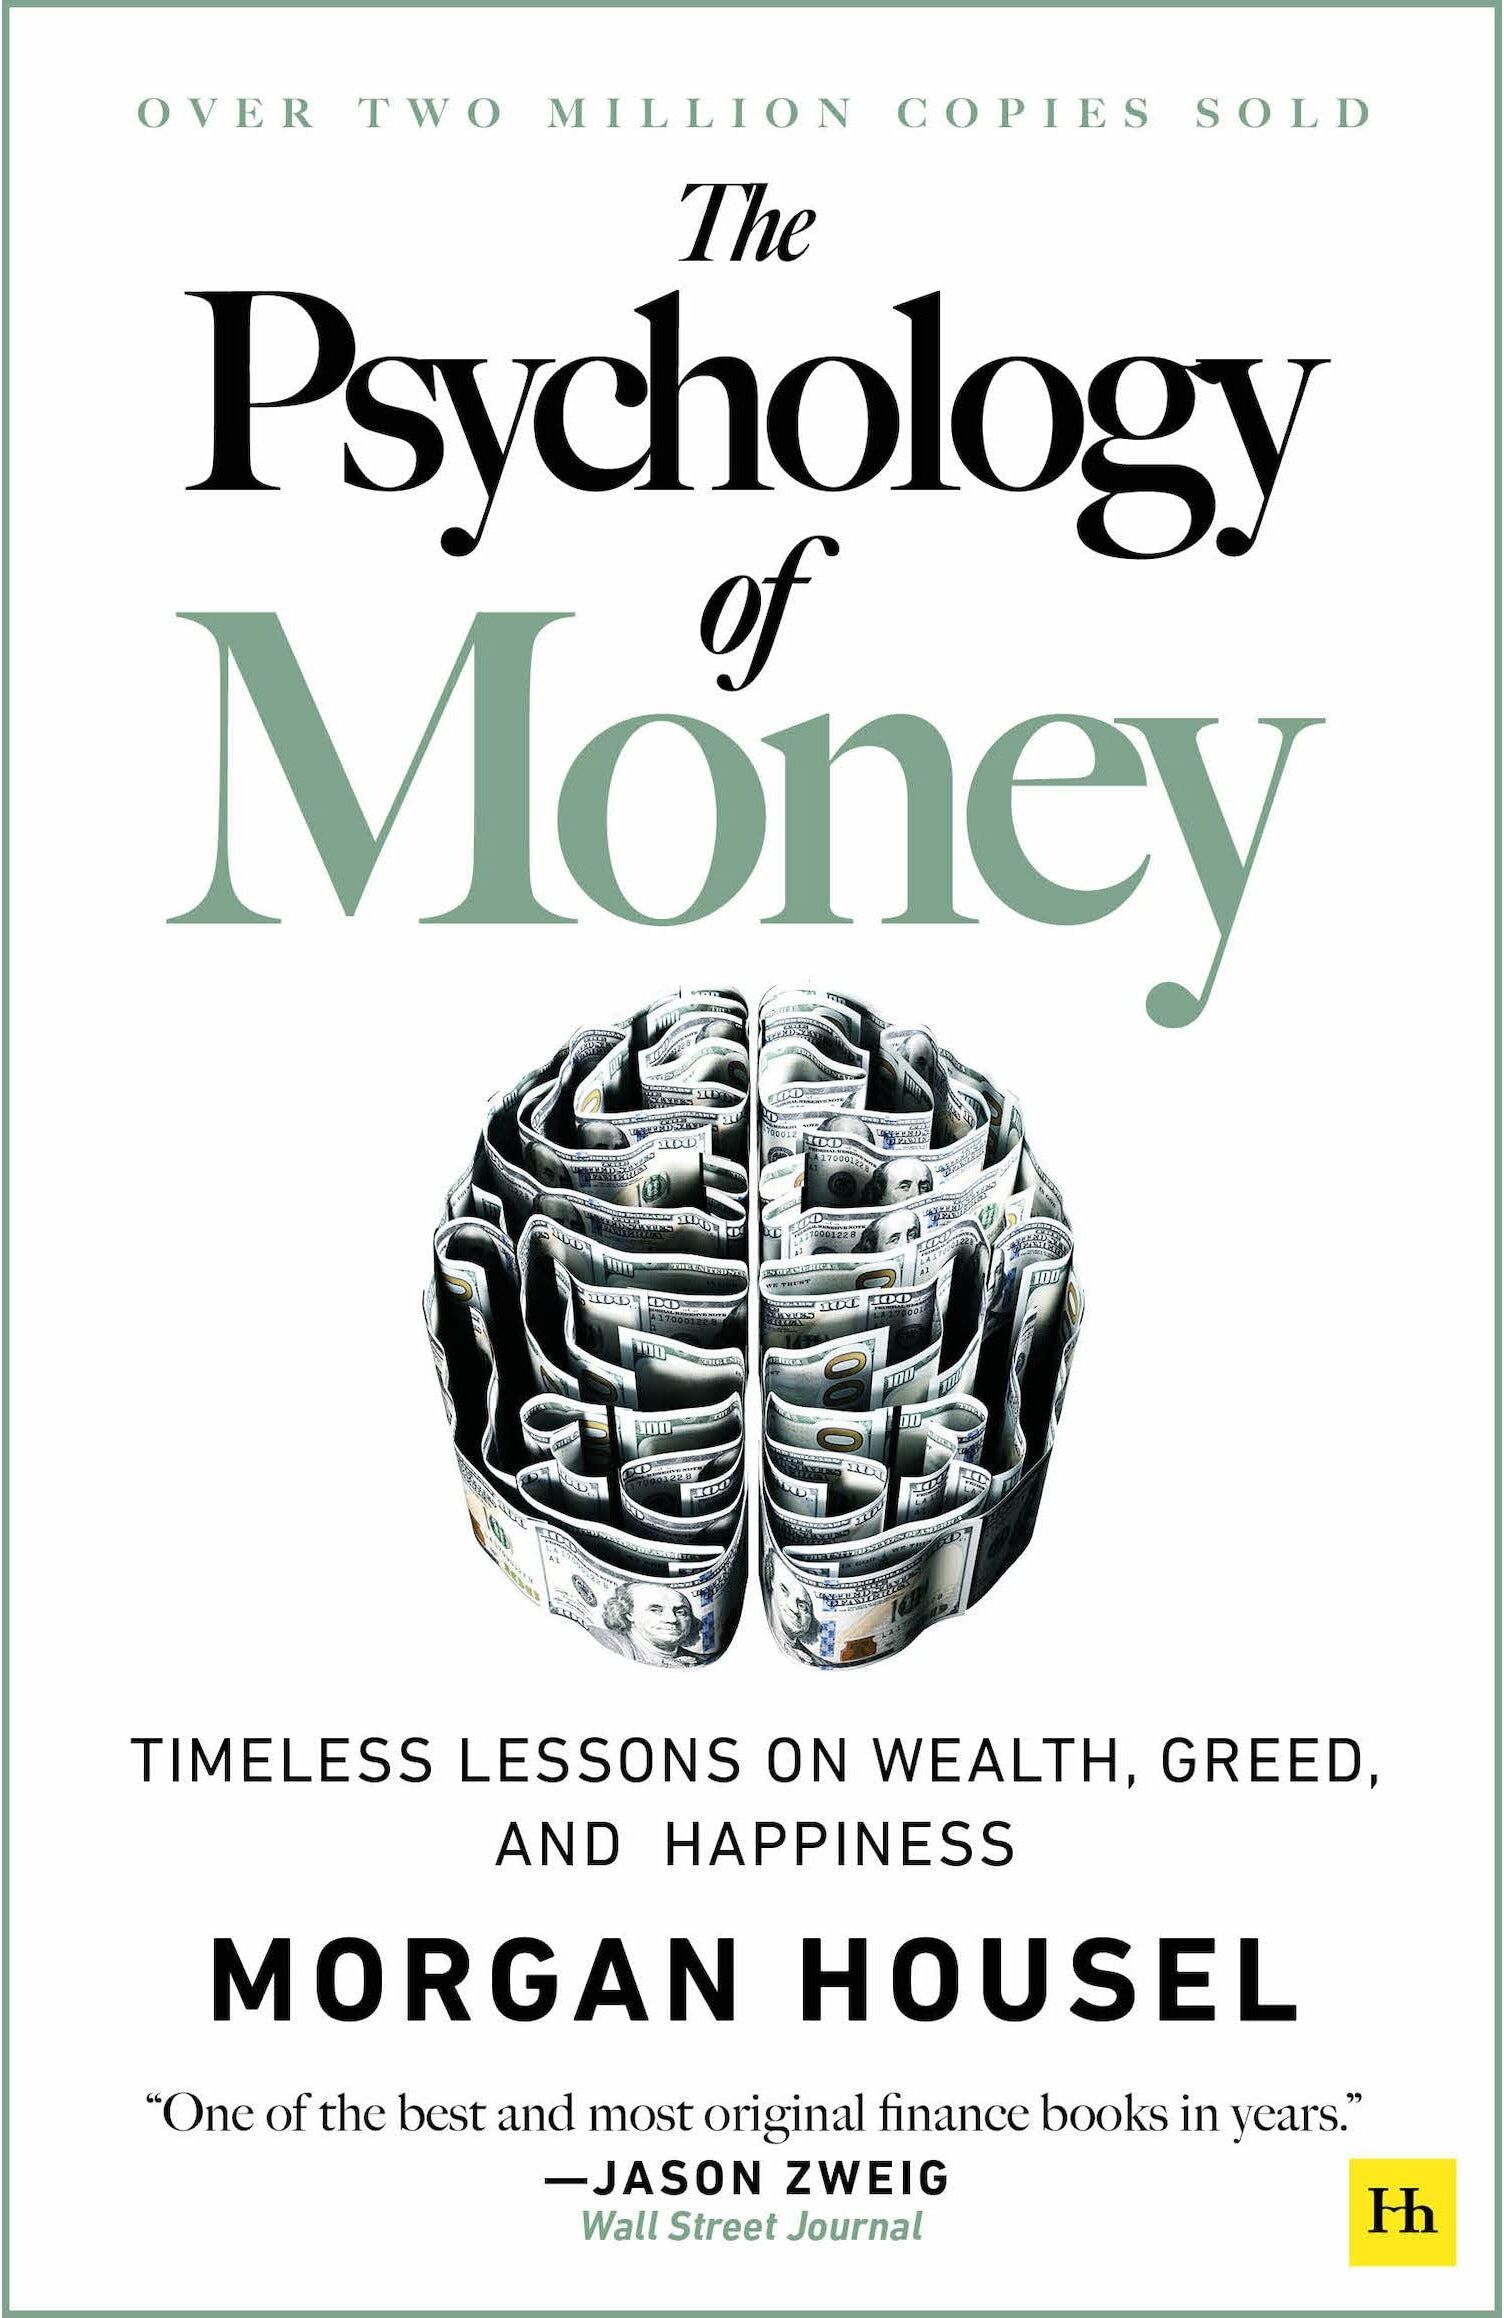
Harriman House The Psychology of Money: Timeless lessons on wealth, greed, and happiness by Morgan HouselDoing well with money isn't necessarily about what you know. It's about how you behave. And behavior is hard to teach, even to really smart people.Money investing, personal finance, and business decisions is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet. They make them at the dinner table, or in a meeting room, where personal history, your own unique view of the world, ego, pride, marketing, and odd incentives are scrambled together.In The Psychology of Money, award-winning author Morgan Housel shares 19 short stories exploring the strange ways people think about money and teaches you how to make better sense of one of life's most important topics.10,99 £*Shipping: 2,99 £Secure redirect to the provider
-
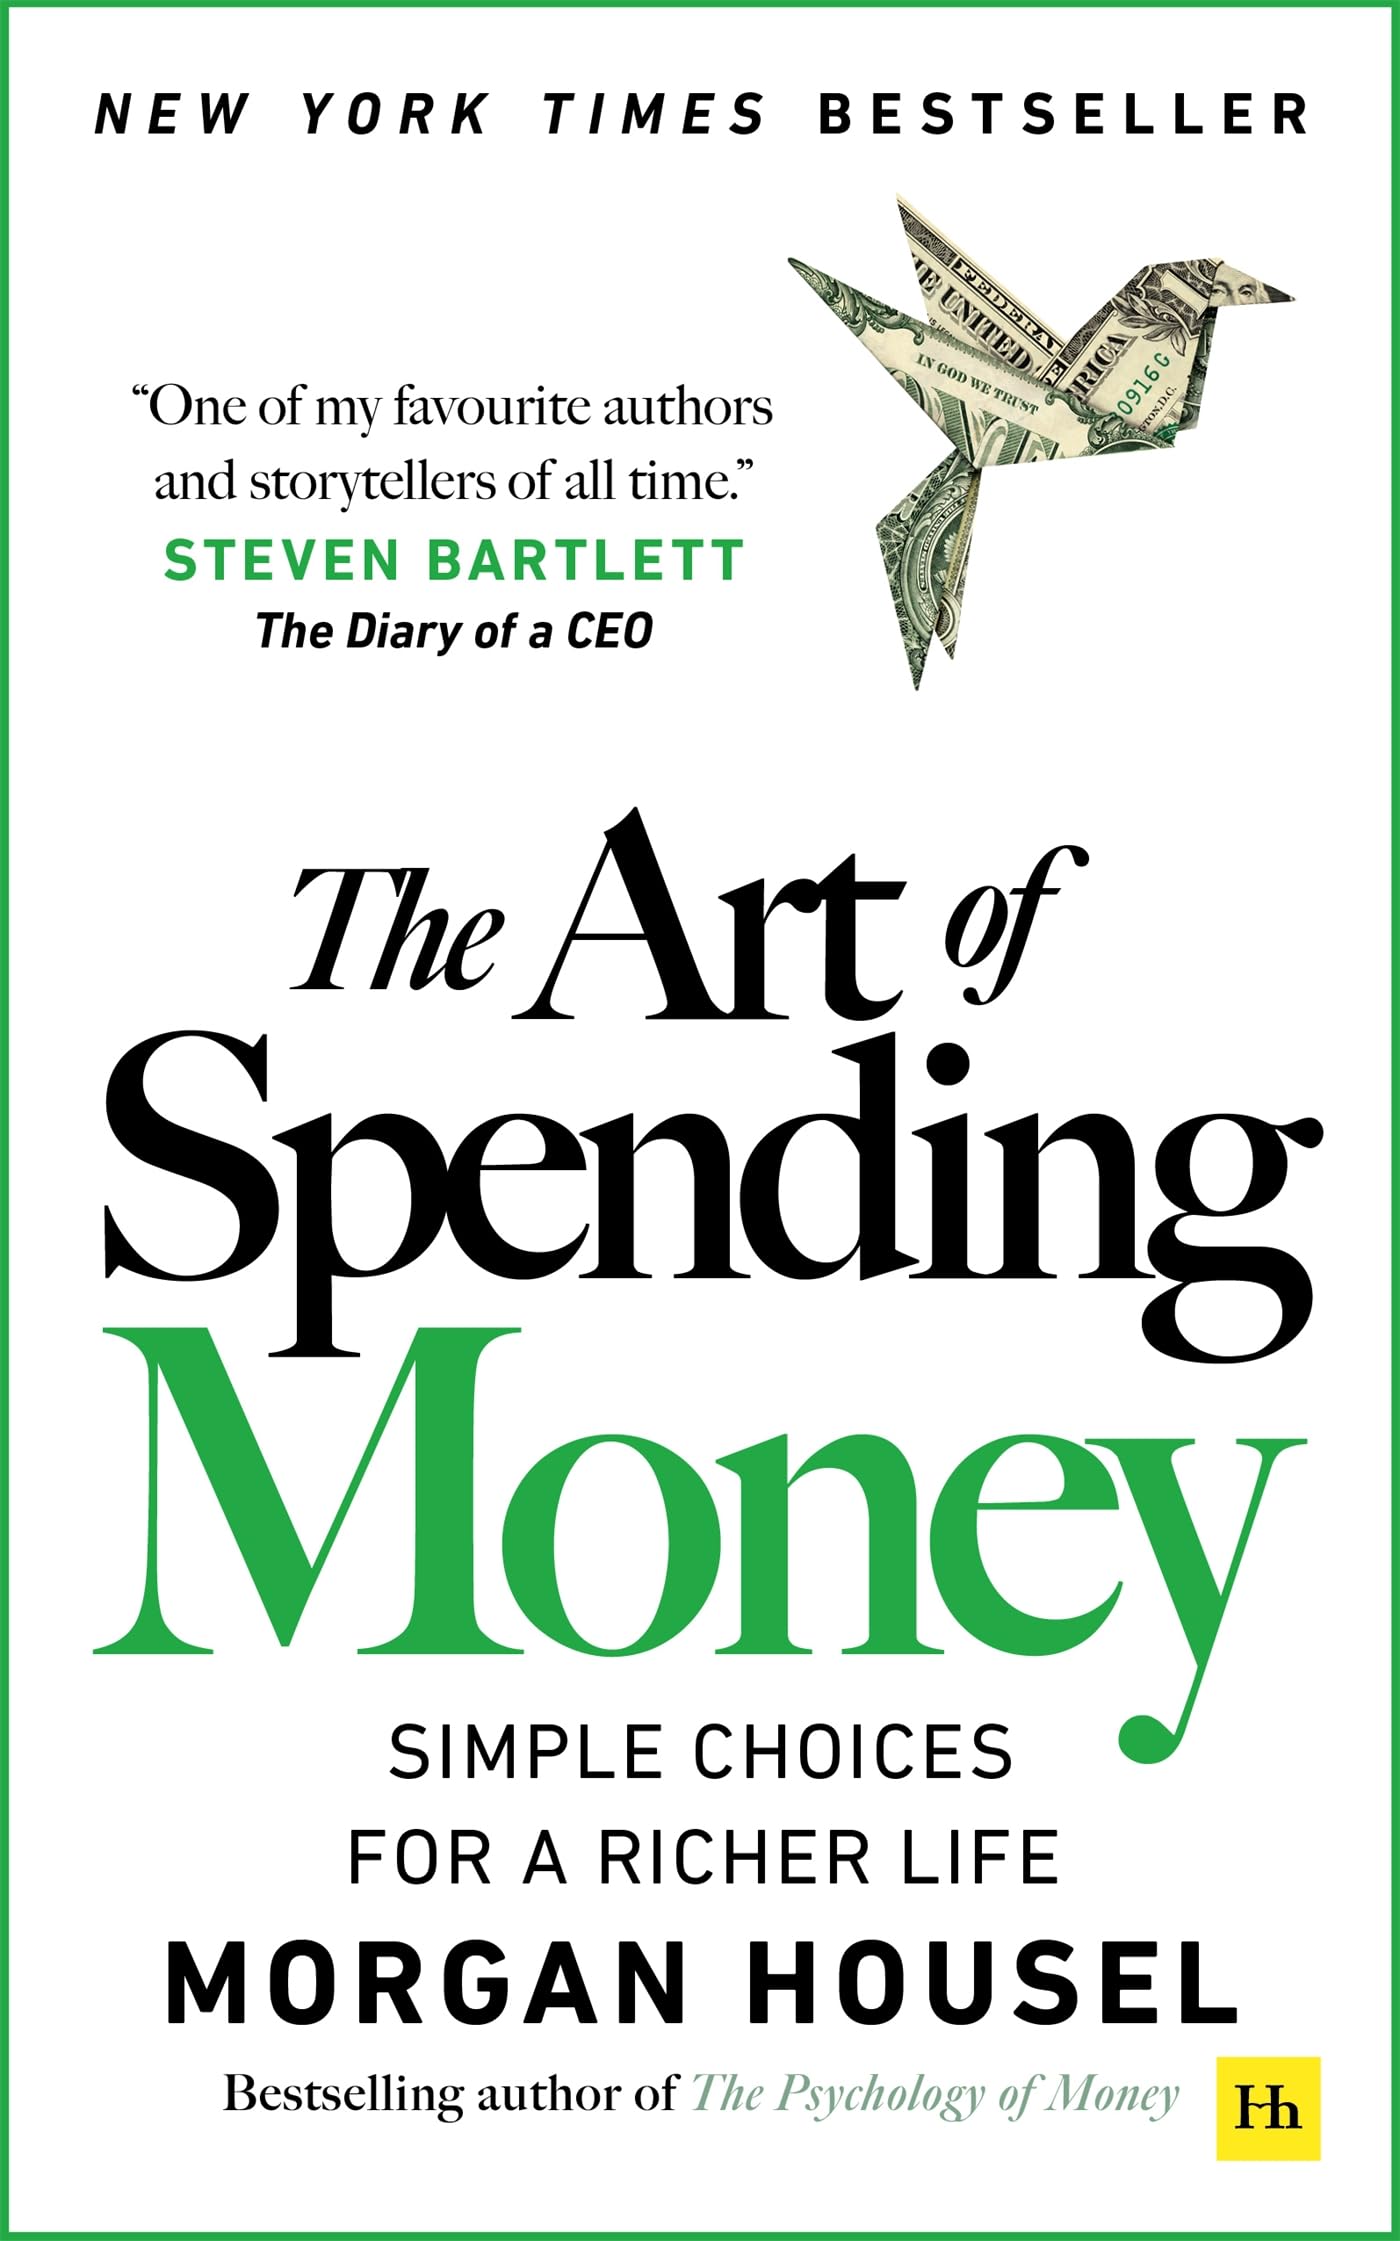
Harriman House The Art of Spending Money: Simple Choices for a Richer Life by Morgan HouselSimple lessons on harnessing the power of money to live a happier life. Can money buy happiness? Yes. Can spending it make you happier? Absolutely. Yet, many of us struggle to unlock its full potential – either by spending on things that don't bring as much joy as they should, or by avoiding investments that would truly enhance our mental well-being. In The Art of Spending Money, award-winning and global bestselling author Morgan Housel offers a refreshingly practical approach to managing wealth while finding deeper meaning and contentment. Instead of cookie-cutter financial advice, Housel provides you with psychological tools to navigate your personal relationship with money and optimise for happiness. Discover why people often mistake envy for admiration, how to align your expectations with your income, and ways to invest in future happiness while avoiding regret. Learn about the dangers of social debt and embrace the radical idea that the fastest way to build wealth is by going slow. The Art of Spending Money delves into the complexities that surround money – envy, social aspirations, identity, and insecurity – crucial aspects often missed in traditional financial books. Armed with new insights into money and wealth, you’ll learn to sidestep common spending traps, make smarter investing choices, and wield money to its fullest potential to enhance your enjoyment of life.10,99 £*Shipping: 2,99 £Secure redirect to the provider
-
What income is required for such a house?
The income required for a house depends on various factors such as the location, size, and cost of the house. Generally, it is recommended that a household's total housing costs should not exceed 30% of their gross income. So, for a house with a higher cost, a higher income would be required to afford the mortgage, property taxes, insurance, and maintenance. Additionally, lenders typically look for a debt-to-income ratio of 43% or lower when considering mortgage applications. Therefore, the income required for such a house would need to be sufficient to cover these expenses while maintaining a healthy financial situation. **
-
What are the living expenses for owning a house with a partner?
Living expenses for owning a house with a partner can include mortgage or rent payments, property taxes, homeowners insurance, utilities (such as water, electricity, gas, and internet), maintenance and repairs, and possibly homeowner association fees. Additionally, there may be other costs such as furnishings, appliances, and home improvement projects. It's important for partners to discuss and budget for these expenses together to ensure they can comfortably afford the costs of homeownership. **
-
Would you accept financial support from family members when buying your house?
As a language model AI, I don't have personal preferences, but I can provide a general perspective. Accepting financial support from family members when buying a house is a personal decision that depends on individual circumstances and relationships. Some people may feel grateful for the support and see it as a way to strengthen family ties, while others may prefer to maintain financial independence. It's important to consider the potential impact on family dynamics and to have open and honest communication about expectations and boundaries. **
-
Can a multi-family house be paid off solely from rental income?
Yes, a multi-family house can potentially be paid off solely from rental income if the rental income generated from the property is sufficient to cover the mortgage payments, property taxes, insurance, and maintenance costs. It would require careful financial planning and budgeting to ensure that the rental income is enough to cover all expenses and pay down the mortgage over time. Additionally, factors such as vacancy rates, market conditions, and unexpected expenses should be taken into consideration when determining if a multi-family house can be paid off solely from rental income. **

How can one afford a house with an income of 60000 euros?
With an income of 60000 euros, one can afford a house by carefully budgeting and saving for a down payment. It is important to prioritize saving and cutting down on unnecessary expenses to increase the amount available for a down payment. Additionally, exploring different mortgage options and finding a property within one's budget are crucial steps in affording a house with a 60000 euro income. Consideration of additional sources of income or financial assistance programs may also be helpful in achieving the goal of homeownership. **
Can I buy a house with a net income of 2000 euros?
It may be challenging to buy a house with a net income of 2000 euros, as it depends on various factors such as the cost of the house, the amount of savings you have, and the availability of mortgage options. Generally, lenders consider your income, credit score, and existing debt when determining your eligibility for a mortgage. It's important to carefully assess your financial situation and consider saving for a larger down payment or increasing your income before pursuing a home purchase. Consulting with a financial advisor or mortgage lender can provide more personalized guidance. **
Top-Angebote
Products related to Thorsons-Cornerstone-Harriman-House:
-
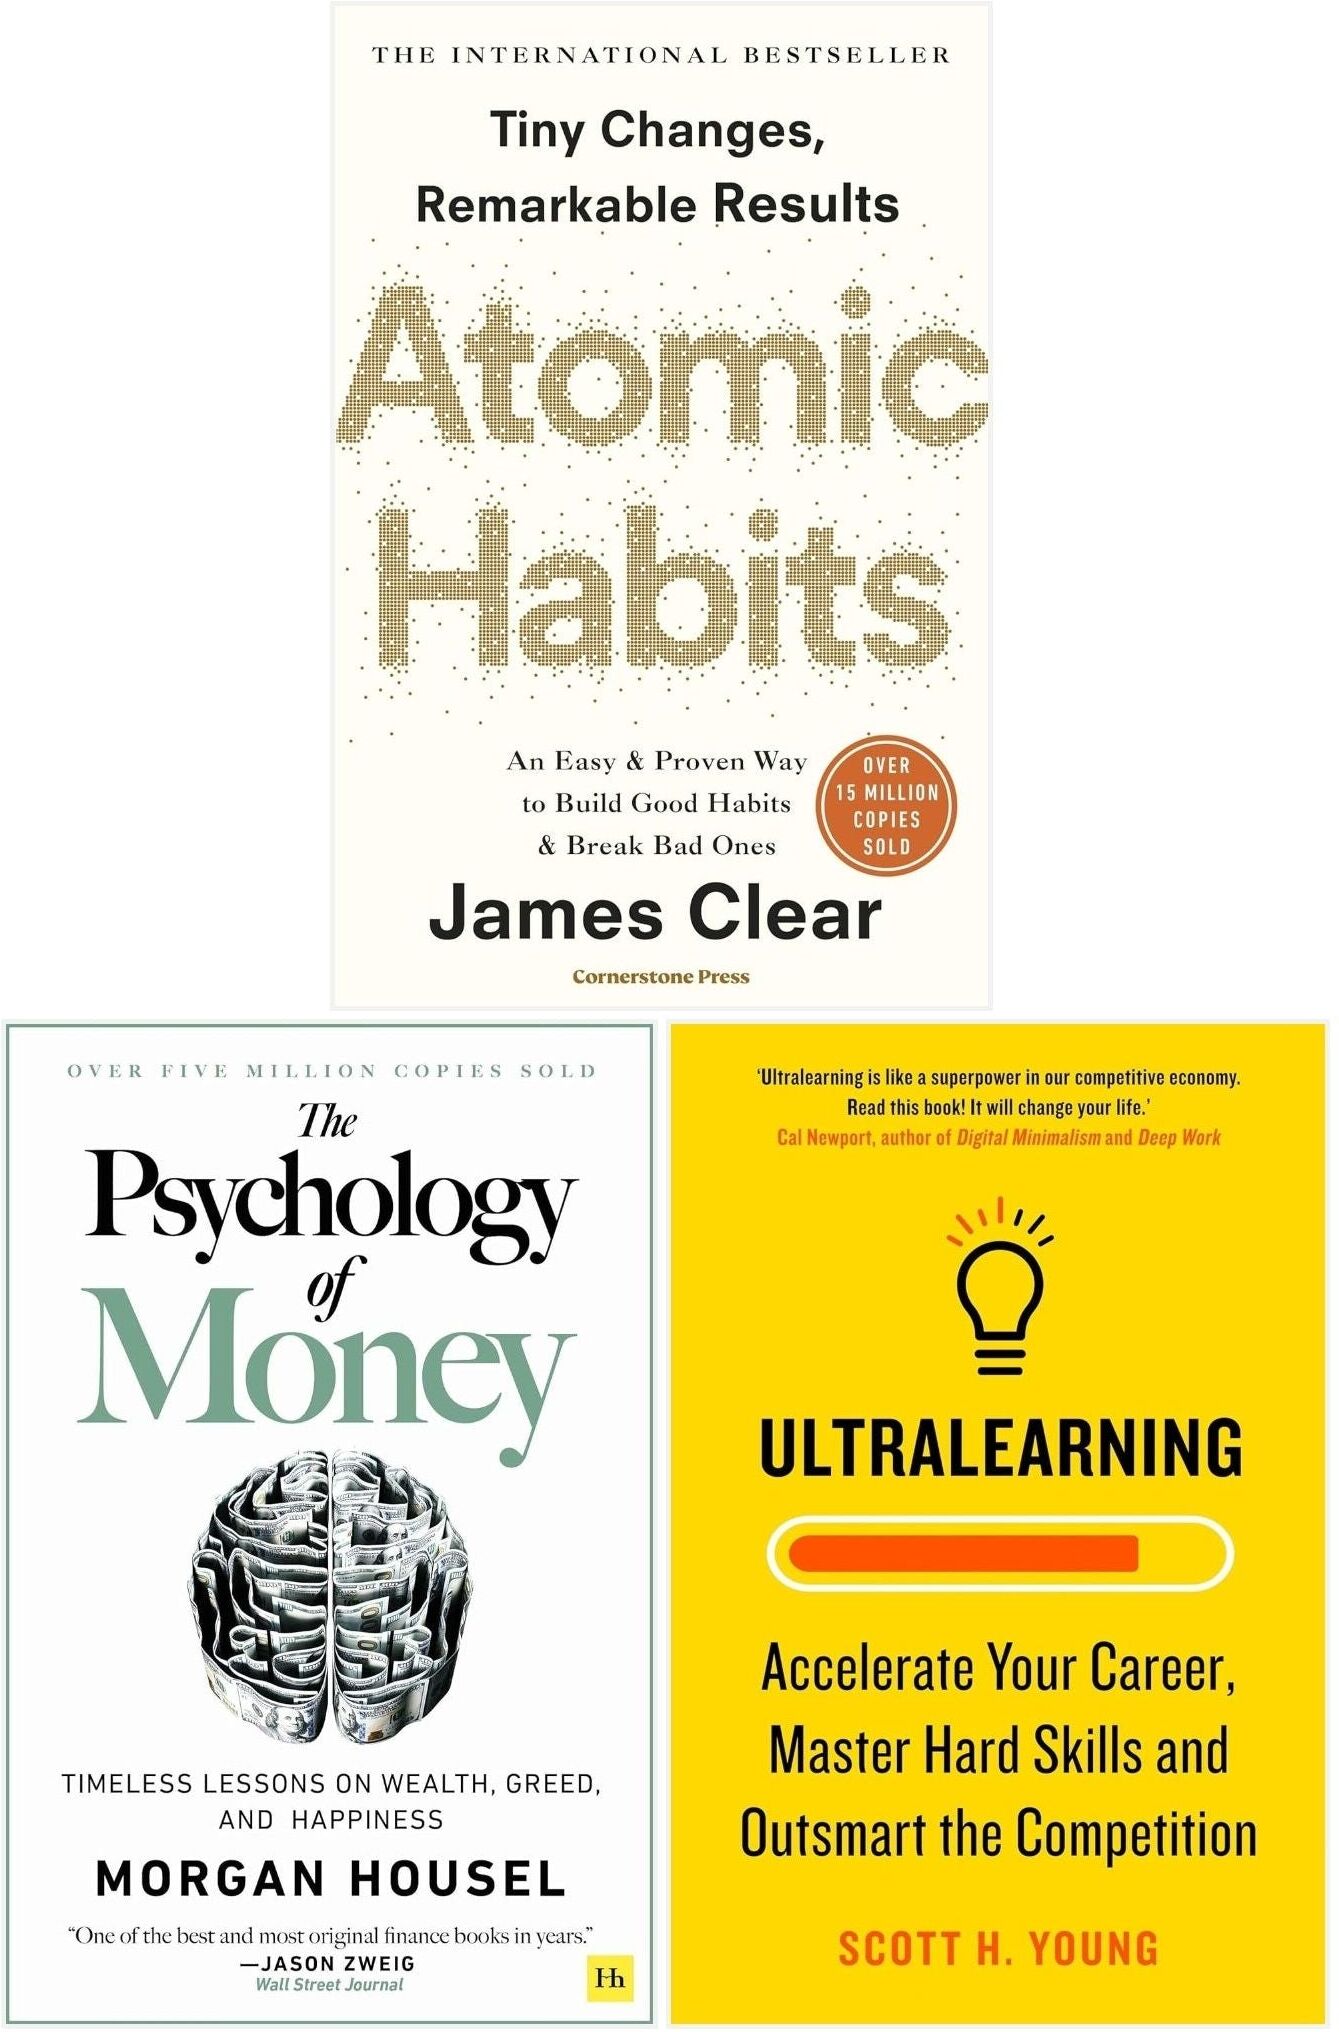
Thorsons/Cornerstone/Harriman House Ultralearning, Atomic Habits and The Psychology of Money 3 Books SetUltralearning Future-proof your career and maximize your competitive advantage by learning the skill necessary to stay relevant, reinvent yourself, and adapt to whatever the workplace throws your way in this essential guide. Faced with tumultuous economic times and rapid technological change, staying ahead in your career depends on continual learning―a lifelong mastery of new ideas, subjects, and skills. If you want to accomplish more and stand apart from everyone else, you need to become an ultralearner. Atomic Habits Transform your life with tiny changes in behaviour, starting now. People think that when you want to change your life, you need to think big. But world-renowned habits expert James Clear has discovered another way. He knows that real change comes from the compound effect of hundreds of small decisions: doing two push-ups a day, waking up five minutes early, or holding a single short phone call. The Psychology of Money Doing well with money isn't necessarily about what you know. It's about how you behave. And behavior is hard to teach, even to really smart people. Money investing, personal finance, and business decisions is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet. They make them at the dinner table, or in a meeting room, where personal history, your own unique view of the world, ego, pride, marketing, and odd incentives are scrambled together.29,99 £*Shipping: 2,99 £Secure redirect to the provider
-
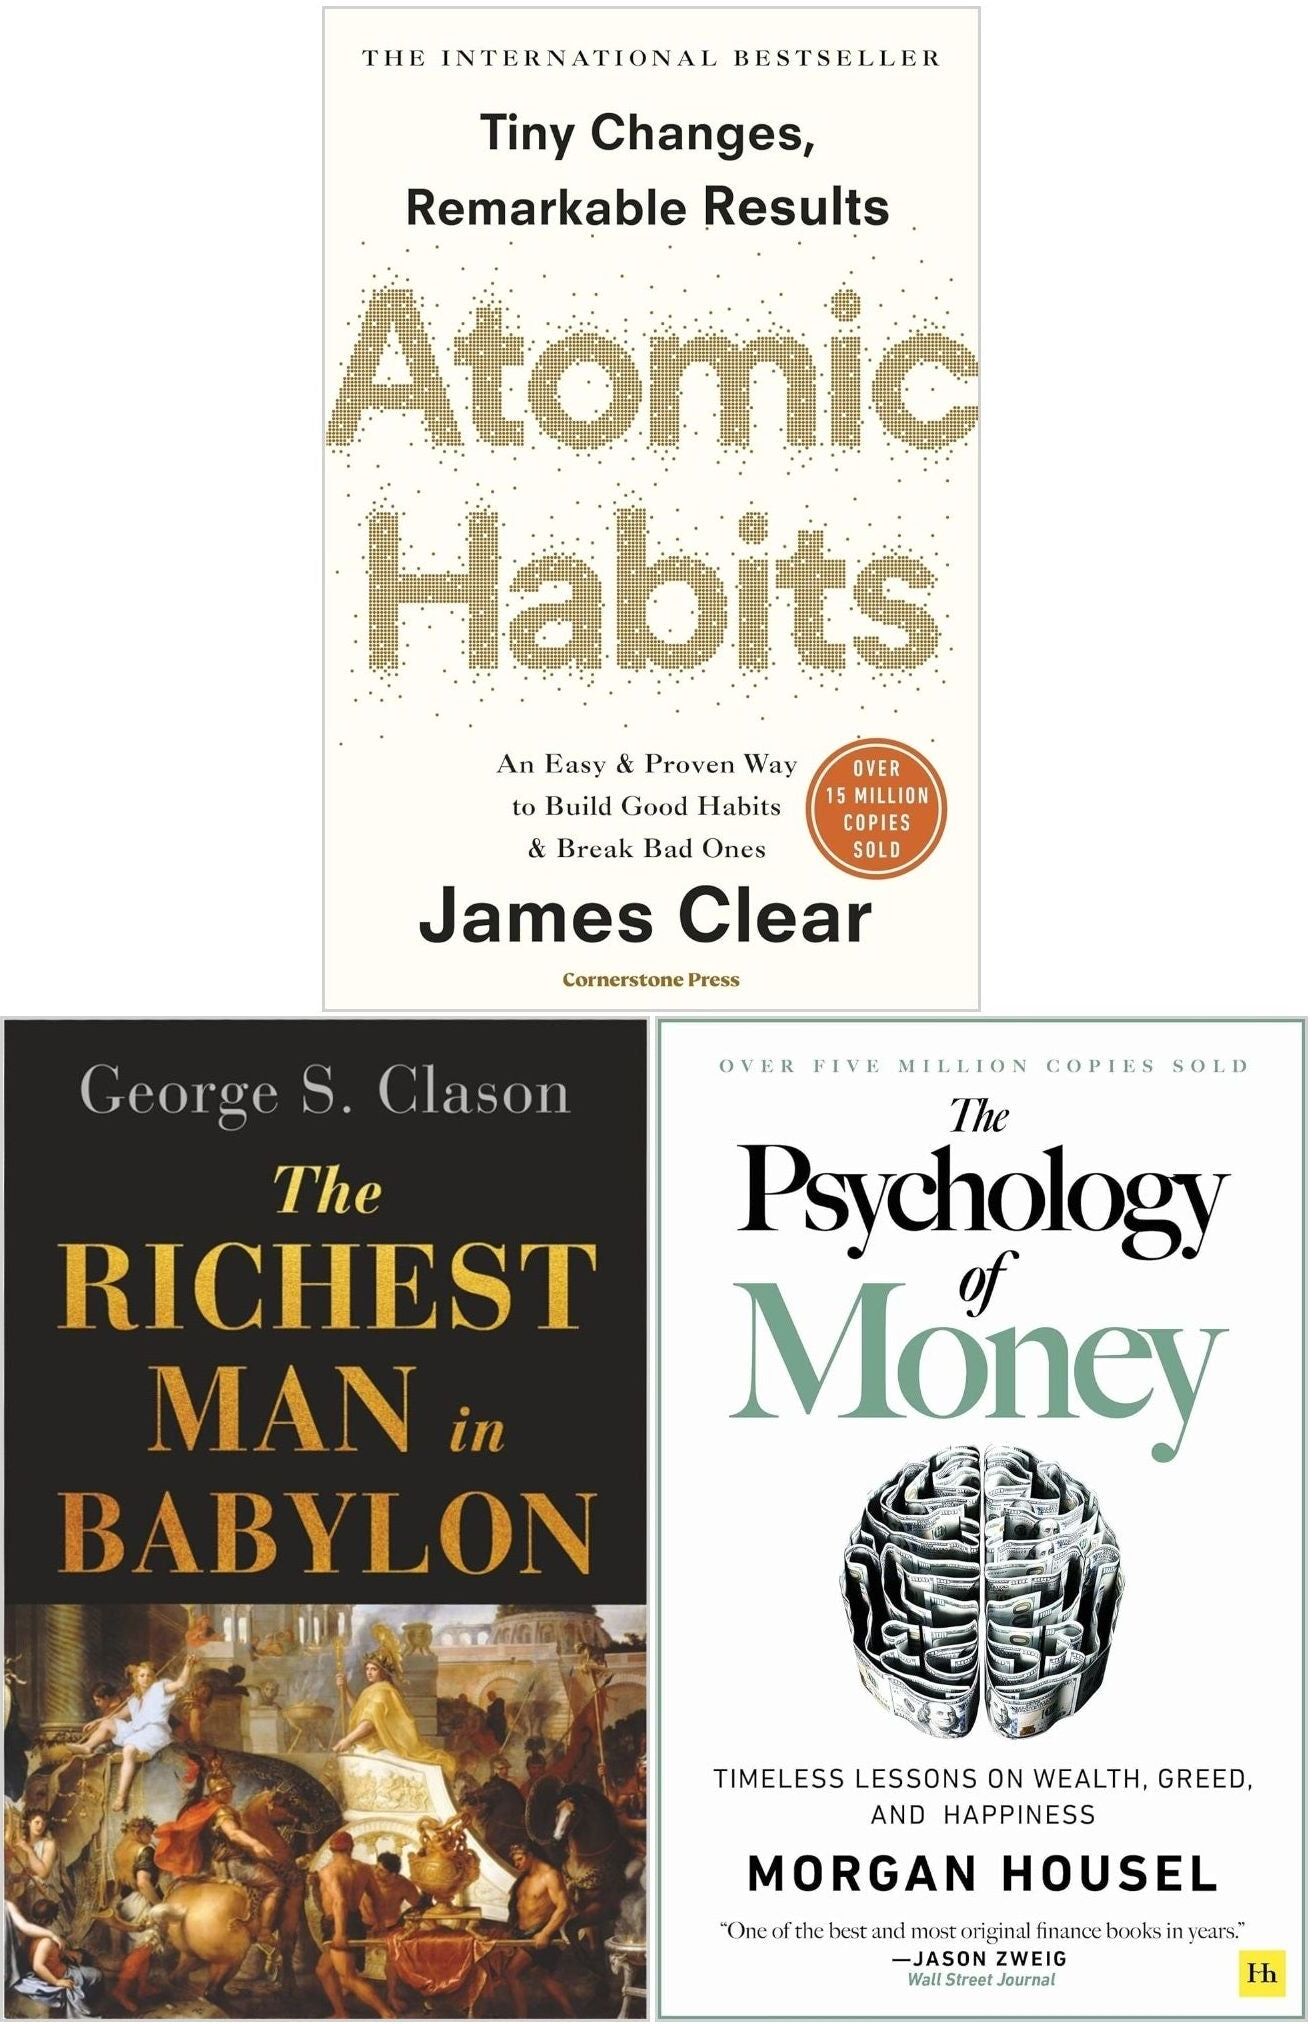
Wilco/Harriman House/Cornerstone The Richest Man In Babylon, The Psychology of Money and Atomic Habits 3 Books SetThe Richest Man In Babylon by George S. Clason This inspirational book is hailed as the greatest of books on finances. It unveils the secrets to wealth, providing priceless suggestions, advice, unforgettable parables, financial problem solving tools, and invaluable information which will get you on your way to riches. It is a must read for all who want financial stability. It rapidly became one of the best-selling books of all time. Through a series of enlightening parables set in the heart of ancient Babylon, Clason provided his readers with economic tips and tools for financial success. The Psychology of Money by Morgan Housel Doing well with money isn't necessarily about what you know. It's about how you behave. And behavior is hard to teach, even to really smart people. Money – investing, personal finance, and business decisions – is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet. They make them at the dinner table, or in a meeting room, where personal history, your own unique view of the world, ego, pride, marketing, and odd incentives are scrambled together. Atomic Habits by James Clear Transform your life with tiny changes in behaviour, starting now. People think that when you want to change your life, you need to think big. But world-renowned habits expert James Clear has discovered another way. He knows that real change comes from the compound effect of hundreds of small decisions: doing two push-ups a day, waking up five minutes early, or holding a single short phone call. He calls them atomic habits.22,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Harriman House Atomic Habits, The Compound Effect, The Psychology of Money 3 Books Collection SetAtomic Habits People think that when you want to change your life, you need to think big. But world-renowned habits expert James Clear has discovered another way. He knows that real change comes from the compound effect of hundreds of small decisions: doing two push-ups a day, waking up five minutes early, or holding a single short phone call. The Compound Effect As the central curator of the success media industry for over 25 years, author Darren Hardy has heard it all, seen it all, and tried most of it. This book reveals the core principles that drive success. The Compound Effect contains the essence of what every superachiever needs to know, practice, and master to obtain extraordinary success. Inside you will find strategies on: How to win--every time! The Psychology of Money Doing well with money isn't necessarily about what you know. It's about how you behave. And behavior is hard to teach, even to really smart people. Money investing, personal finance, and business decisions is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet.22,95 £*Shipping: 2,99 £Secure redirect to the provider
-
Random House Business/Harriman House ltd Atomic Habits & The Psychology of Money – 2 Books Collection Set Personal Growth, Wealth & Mindset BestsellersAtomic Habits People think that when you want to change your life, you need to think big. But world-renowned habits expert James Clear has discovered another way. He knows that real change comes from the compound effect of hundreds of small decisions: doing two push-ups a day, waking up five minutes early, or holding a single short phone call. He calls them atomic habits. In this ground-breaking book, Clears reveals exactly how these minuscule changes can grow into such life-altering outcomes. He uncovers a handful of simple life hacks (the forgotten art of Habit Stacking, the unexpected power of the Two Minute Rule, or the trick to entering the Goldilocks Zone), and delves into cutting-edge psychology and neuroscience to explain why they matter. Along the way, he tells inspiring stories of Olympic gold medalists, leading CEOs, and distinguished scientists who have used the science of tiny habits to stay productive, motivated, and happy. The Psychology of Money Doing well with money isn't necessarily about what you know. It's about how you behave. And behaviour is hard to teach, even to really smart people. Money investing, personal finance, and business decisions is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet. They make them at the dinner table, or in a meeting room, where personal history, your own unique view of the world, ego, pride, marketing, and odd incentives are scrambled together. In The Psychology of Money, award-winning author Morgan Housel shares 19 short stories exploring the strange ways people think about money and teaches you how to make better sense of one of life's most important topics.15,99 £*Shipping: 2,99 £Secure redirect to the provider
-
What are deductible expenses for a house?
Deductible expenses for a house typically include mortgage interest, property taxes, and mortgage insurance premiums. Additionally, expenses related to home office use, certain home improvements for medical purposes, and energy-efficient home upgrades may also be deductible. It's important to keep detailed records and consult with a tax professional to ensure you are correctly identifying and claiming all eligible deductions for your home. **
-
What expenses do I have after buying a house?
After buying a house, you will have ongoing expenses such as property taxes, homeowner's insurance, and possibly private mortgage insurance (PMI) if you put down less than 20% as a down payment. You will also have to budget for maintenance and repairs, as well as utilities such as water, electricity, and gas. Additionally, if you have a mortgage, you will have monthly mortgage payments that include principal and interest. It's important to budget for these expenses to ensure you can comfortably afford homeownership. **
-
What income is required for such a house?
The income required for a house depends on various factors such as the location, size, and cost of the house. Generally, it is recommended that a household's total housing costs should not exceed 30% of their gross income. So, for a house with a higher cost, a higher income would be required to afford the mortgage, property taxes, insurance, and maintenance. Additionally, lenders typically look for a debt-to-income ratio of 43% or lower when considering mortgage applications. Therefore, the income required for such a house would need to be sufficient to cover these expenses while maintaining a healthy financial situation. **
-
What are the living expenses for owning a house with a partner?
Living expenses for owning a house with a partner can include mortgage or rent payments, property taxes, homeowners insurance, utilities (such as water, electricity, gas, and internet), maintenance and repairs, and possibly homeowner association fees. Additionally, there may be other costs such as furnishings, appliances, and home improvement projects. It's important for partners to discuss and budget for these expenses together to ensure they can comfortably afford the costs of homeownership. **
Similar search terms for Thorsons-Cornerstone-Harriman-House
-
Harriman House The Psychology of Money: Timeless lessons on wealth, greed, and happiness by Morgan HouselDoing well with money isn't necessarily about what you know. It's about how you behave. And behavior is hard to teach, even to really smart people.Money investing, personal finance, and business decisions is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet. They make them at the dinner table, or in a meeting room, where personal history, your own unique view of the world, ego, pride, marketing, and odd incentives are scrambled together.In The Psychology of Money, award-winning author Morgan Housel shares 19 short stories exploring the strange ways people think about money and teaches you how to make better sense of one of life's most important topics.10,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Harriman House The Art of Spending Money: Simple Choices for a Richer Life by Morgan HouselSimple lessons on harnessing the power of money to live a happier life. Can money buy happiness? Yes. Can spending it make you happier? Absolutely. Yet, many of us struggle to unlock its full potential – either by spending on things that don't bring as much joy as they should, or by avoiding investments that would truly enhance our mental well-being. In The Art of Spending Money, award-winning and global bestselling author Morgan Housel offers a refreshingly practical approach to managing wealth while finding deeper meaning and contentment. Instead of cookie-cutter financial advice, Housel provides you with psychological tools to navigate your personal relationship with money and optimise for happiness. Discover why people often mistake envy for admiration, how to align your expectations with your income, and ways to invest in future happiness while avoiding regret. Learn about the dangers of social debt and embrace the radical idea that the fastest way to build wealth is by going slow. The Art of Spending Money delves into the complexities that surround money – envy, social aspirations, identity, and insecurity – crucial aspects often missed in traditional financial books. Armed with new insights into money and wealth, you’ll learn to sidestep common spending traps, make smarter investing choices, and wield money to its fullest potential to enhance your enjoyment of life.10,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Harriman House Same as Ever & The Psychology Of Money 2 Books Collection Set by Morgan HouselTitles in this set:1. Same as Ever2. The Psychology of MoneyDescription:Same as Ever When planning for the future we often ask, “What will the economy be doing this time next year?” Or, “What will be different ten years from now?”But forecasting is hard. The important events that will shape the future are inherently unpredictable.Instead, we should be asking a different question:What will be the same ten years from now?What will be the same one hundred years from now?Knowledge of the things that never change is more useful, and more important, than an uncertain prediction of an unknowable future.In Same As Ever, bestselling author Morgan Housel shares 24 short stories about the ways that life, behaviour, and business will always be the same.Armed with this knowledge of the unchanging, you will have a powerful new ability to think about risk, opportunity, and how to navigate the uncertainty of the future.The Psychology of Money Doing well with money isn't necessarily about what you know. It's about how you behave. And behavior is hard to teach, even to really smart people.Money investing, personal finance, and business decisions is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet. They make them at the dinner table, or in a meeting room, where personal history, your own unique view of the world, ego, pride, marketing, and odd incentives are scrambled together.In The Psychology of Money, award-winning author Morgan Housel shares 19 short stories exploring the strange ways people think about money and teaches you how to make better sense of one of life's most important topics.14,50 £*Shipping: 2,99 £Secure redirect to the provider
-
Harriman House Same as Ever: Timeless Lessons on Risk, Opportunity and Living a Good Life by Morgan HouselThe New York Times and Sunday Times Bestseller.As seen on Diary of a CEO podcast with Steven Bartlett.From the author of the multi-million copy selling The Psychology of Money…Same As Ever will arm you with a powerful new ability to think about risk and opportunity, and navigate the uncertainty of the future. When planning for the future, we often ask something like, “What will the economy be doing this time next year?” Or we want to know, “What will be different ten years from now?”But forecasting is hard. The important events that will shape the future are inherently unpredictable.Instead, we should be asking a different question: What will be the same in the future as it is now?Knowledge of the things that never change is more useful, and more important, than an uncertain prediction of an unknowable future.In Same As Ever, bestselling author Morgan Housel shares 24 short stories about the ways that life, behaviour, and business will always be the same.As you see familiar themes repeat again and again in the years ahead, you’ll find yourself nodding and saying, “Yep, same as ever.”With this new knowledge and confidence, you will be on the path to living a good life.4,99 £*Shipping: 1,99 £Secure redirect to the provider
-
Would you accept financial support from family members when buying your house?
As a language model AI, I don't have personal preferences, but I can provide a general perspective. Accepting financial support from family members when buying a house is a personal decision that depends on individual circumstances and relationships. Some people may feel grateful for the support and see it as a way to strengthen family ties, while others may prefer to maintain financial independence. It's important to consider the potential impact on family dynamics and to have open and honest communication about expectations and boundaries. **
-
Can a multi-family house be paid off solely from rental income?
Yes, a multi-family house can potentially be paid off solely from rental income if the rental income generated from the property is sufficient to cover the mortgage payments, property taxes, insurance, and maintenance costs. It would require careful financial planning and budgeting to ensure that the rental income is enough to cover all expenses and pay down the mortgage over time. Additionally, factors such as vacancy rates, market conditions, and unexpected expenses should be taken into consideration when determining if a multi-family house can be paid off solely from rental income. **
-
How can one afford a house with an income of 60000 euros?
With an income of 60000 euros, one can afford a house by carefully budgeting and saving for a down payment. It is important to prioritize saving and cutting down on unnecessary expenses to increase the amount available for a down payment. Additionally, exploring different mortgage options and finding a property within one's budget are crucial steps in affording a house with a 60000 euro income. Consideration of additional sources of income or financial assistance programs may also be helpful in achieving the goal of homeownership. **
-
Can I buy a house with a net income of 2000 euros?
It may be challenging to buy a house with a net income of 2000 euros, as it depends on various factors such as the cost of the house, the amount of savings you have, and the availability of mortgage options. Generally, lenders consider your income, credit score, and existing debt when determining your eligibility for a mortgage. It's important to carefully assess your financial situation and consider saving for a larger down payment or increasing your income before pursuing a home purchase. Consulting with a financial advisor or mortgage lender can provide more personalized guidance. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.