Buy bilanzierung.eu ?
We are moving the project
bilanzierung.eu .
Are you interested in purchasing the domain
bilanzierung.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy bilanzierung.eu ?
What are transitory assets and/or liabilities?
Transitory assets and/or liabilities are items on a company's balance sheet that are expected to be settled or used up within a relatively short period of time, typically within one year. These items are considered to be temporary in nature and are not expected to have a long-term impact on the company's financial position. Examples of transitory assets include cash, accounts receivable, and inventory, while examples of transitory liabilities include accounts payable and short-term debt. It is important for investors and analysts to understand the nature of these transitory items when evaluating a company's financial health and performance. **
How are the assets and liabilities evaluated?
Assets and liabilities are evaluated based on their current market value or book value. For assets, this means determining their fair market value, which is the price that they could be sold for in the current market. Liabilities are evaluated based on their current outstanding balance or the amount that is owed. This evaluation helps to determine the financial health and position of a company, as well as its ability to meet its financial obligations. **
Similar search terms for Property
Top-Angebote
Products related to Property:
-
NARS Sparked Liquid Eyeshadow liquid glitter eyeshadow shade HOT PROPERTY 3.5 mlNARS Sparked Liquid Eyeshadow, 3.5 ml, Eyeshadows for Women, Do you tend to hit the same few shades in your favourite eyeshadow palette but you just can’t do without them? Or are you travelling and can only fit the essentials in your toiletry bag? Thanks to its compact size, the NARS Sparked Liquid Eyeshadow eyeshadow won’t take up much room, so you can always have it on hand, be it by itself in your purse or as an accessory to your favourite palette. This allows you to give your lids a pop of colour or define the shape of your eyes to your liking, giving every makeup look a new dimension, no matter what your reason for getting them is. The formula ensures even pigment coverage, easy application and seamless blending without unwanted harsh transitions. Characteristics: long-lasting do not smudge in the crease of the eyelid washes out easily sparkling effect ophthalmologically tested30,80 £*Shipping: 3,99 £Secure redirect to the provider
-
J H Haynes & Co Ltd Haynes Period Property Manual: Care And Repair Of Old HousesHaynes Period Property Manual: Care And Repair Of Old Houses Britain has a wonderfully rich stock of period houses - everything from medieval cottages to Georgian townhouses and Edwardian mansions. But many of these historic properties are now at risk. Some are unwittingly damaged by well-meaning owners or incompetent builders; others suffer long-term deterioration where mortgage lenders have imposed quick-fix 'remedies'. Despite being some of the most sustainable buildings on the planet; many old houses are now being subjected to ill-advised works to upgrade thermal efficiency; resulting in the destruction of the very qualities that make them so appealing; slashing their values. Haynes have come to the rescue with this clearly written; lavishly illustrated manual explaining the correct approach to care and repair - covering the full range of traditional materials.10,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Quercus Financial Joy: Set your financial goals for 2026 - Banish Debt, Grow Your Money and Unlock Financial Freedom by Ken and Mary OkoroaforAs seen on ITV's This Morning! A life-changing 10-week plan to help you to turn your life around and design a path to financial freedom, enriched with the small experiences that bring you joy. Stop worrying about money. Start enjoying your life. You might be struggling in debt, living paycheque to paycheque, or worried about preparing for retirement; maybe you're considering your first investment, or you just want an escape plan from the '9 to 5'. Wherever you are on your journey, this book will revolutionize your lifestyle and your relationship with money. Authors Ken and Mary Okoroafor started out as resource-poor, working-class immigrants and have built a life of financial independence and joyful moments through hard work, smart saving and savvy investing. They know what it feels like to start from ground zero, and as a chartered accountant and former CFO, Ken shares his financial expertise to help you unlock the secret to building wealth. You'll learn how to take control of your finances, develop good money habits, become debt-free, invest in assets and multiply your income so you can create the freedom to travel, spend time with your loved ones and plan for a stress-free (early) retirement - all whilst prioritising your wellbeing and having fun! It also includes a dozen real-life interviews with singles, couples and those with children, from different backgrounds, age groups and stages of their money journey, including a few well-known public figures. Financial joy can be achieved by anyone - and it can start today, not tomorrow.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
HP 12c Platinum Financial Calculator (F2231AA)HP 12c Platinum Financial Calculator; Box includes Calculator, batteries, user manual, pouch. Display Description: 10 x 7-segment, single line. Built-in Functions: over 130. Character Display Maximum: 10. Entry System Logic: RPN; Algebraic. Graph Display Features: adjustable contrastA time-tested performer, the HP 12c has an easy-to-use layout, one-line LCD display and efficient RPN data entry. Easily calculate loan payments, interest rates and conversions, standard deviation, percent, TVM, NPV, IRR, cash flows, bonds and more. Over 120 built in functions.- Customizing Features.- Keystroke programming Memory capacity: 399 steps.- Time and Date Management.- Date arithmetic.- The Time-Tested Performer.- Business/Financial Features Statistical/Mathematical Features, Time and Date Management, and Customizing Features, Attractive one line x 10-character LCD display, Select business functions at your fingertips, Great mix of statistic, business and math functions, Read display results easily, even at an angle.- Business/Financial Features.- TVM (loans, savings, and leasing) Amortization Bond price and yield to maturity Cash flow analysis NPV, IRR Memory for up to 20 cash flows SL, DB, SOYD depreciation methods % change, % of total.- Statistical/Mathematical Features.- Cumulative statistical analysis Std. deviation, mean, weighted mean Linear regression Forecasting, correlation coefficient Total, £x, £x2, £y, £y2, £xy +, -, x, %, ÷, 1/x, ±, LN, ex, n!.- Ideal for.- Real estate, finance, accounting, economics and business work. Permitted for use on the CFP and CFA Certification Exams, and GARP FRM Exam.40,99 £*Shipping: 0,00 £Secure redirect to the provider


-
What is a statement of assets and liabilities?
A statement of assets and liabilities is a financial document that provides a snapshot of an individual's or organization's financial position at a specific point in time. It lists all the assets, such as cash, investments, property, and equipment, as well as all the liabilities, such as loans, mortgages, and other debts. The statement helps to assess the overall financial health and solvency of the entity by comparing the total assets to the total liabilities. It is an essential tool for financial planning, decision-making, and assessing the ability to meet financial obligations. **
-
How can accounting, liabilities, and receivables be interconnected?
Accounting, liabilities, and receivables are interconnected in the sense that they all play a role in a company's financial health. Liabilities are debts or obligations that a company owes, which are recorded on the balance sheet as part of the accounting process. Receivables, on the other hand, represent money owed to the company by its customers or clients, and are also recorded on the balance sheet as assets. The relationship between these two is that receivables can eventually become liabilities if they are not collected in a timely manner, which can impact the company's financial position. Therefore, proper accounting practices are essential to accurately track and manage both liabilities and receivables to ensure the company's financial stability. **
-
Why must the assets and liabilities be equal in size?
The assets and liabilities must be equal in size because they represent the financial position of a company at a specific point in time. If the assets exceed the liabilities, it may indicate that the company has more resources than it owes, which could be a positive sign of financial health. On the other hand, if the liabilities exceed the assets, it may indicate that the company has more obligations than resources, which could be a sign of financial risk. Therefore, having equal-sized assets and liabilities provides a balanced and accurate representation of the company's financial standing. **
-
What are bank liabilities and bank balances in accounting?
In accounting, bank liabilities refer to the obligations that a bank owes to its customers and other financial institutions. This includes deposits made by customers, such as savings accounts, checking accounts, and certificates of deposit. Bank balances, on the other hand, represent the amount of money that a bank holds in its accounts, including cash reserves and funds deposited with other banks. These balances are crucial for a bank's liquidity and ability to meet its financial obligations. **

How does rainwater from the neighboring property reach our property?
Rainwater from the neighboring property reaches our property through natural drainage patterns and the force of gravity. It may flow downhill or through the soil, eventually reaching our property boundaries. The topography of the land, such as slopes or depressions, can also influence the direction and flow of rainwater towards our property. Additionally, man-made structures like gutters, downspouts, or drainage systems on the neighboring property can direct rainwater towards our property. **
Should property owners have more responsibility for their own property?
Yes, property owners should have more responsibility for their own property. They should be accountable for maintaining their property to ensure the safety and well-being of others. This includes regular maintenance, repairs, and ensuring that their property meets all safety standards. By taking on more responsibility, property owners can contribute to creating a safer and more pleasant environment for everyone. **
Top-Angebote
Products related to Property:
-
J H Haynes & Co Ltd Haynes Property Manual 2 Books Collection Set (The Victorian House, Period Property)The Victorian House Manual The Victorian House Manual (2nd Edition): How They Were Built, Improvements & Refurbishment, Solutions to All Common Defects Thinking of buying a Victorian or Edwardian house? Or maybe you already own one? Either way, this clearly written manual explains all you need to know about the care and repair of these classic properties. Today, many houses of this age are in need of extensive updating and maintenance, having suffered years of neglect. Some have been damaged by misguided home improvements or botched repairs using the wrong materials. Even newly refurbished properties can sometimes conceal dangerous structural alterations and shoddy build-quality. This unique manual provides detailed, expert advice, backed up with clear how to colour photographs, describing where to check for the critical danger signs and how to fix all common defects. Period Property Britain has a wonderfully rich stock of period houses - everything from medieval cottages to Georgian townhouses and Edwardian mansions. But many of these historic properties are now at risk. Some are unwittingly damaged by well-meaning owners or incompetent builders; others suffer long-term deterioration where mortgage lenders have imposed quick-fix 'remedies'. Despite being some of the most sustainable buildings on the planet, many old houses are now being subjected to ill-advised works to upgrade thermal efficiency, resulting in the destruction of the very qualities that make them so appealing, slashing their values. Haynes have come to the rescue with this clearly written, lavishly illustrated manual explaining the correct approach to care and repair - covering the full range of traditional materials. Every old house has a story to tell, so Haynes also show how to explore your home's history and strip back modern finishes to reveal long lost original features. This comprehensive manual is essential reading whether you want to get your hands dirty or just want to understand how old houses work and how to go about employing specialist craftsmen.19,99 £*Shipping: 2,99 £Secure redirect to the provider
-
J H Haynes & Co Ltd Haynes Property Manual 3 Books Collection Set Home Extension The Victorian House Period PropertyTitles In this Set: The Victorian House Manual Home Extension Period Property The Victorian House Manual The Victorian House Manual (2nd Edition): How They Were Built, Improvements & Refurbishment, Solutions to All Common Defects Thinking of buying a Victorian or Edwardian house? Or maybe you already own one? Either way, this clearly written manual explains all you need to know about the care and repair of these classic properties. Today, many houses of this age are in need of extensive updating and maintenance, having suffered years of neglect. Some have been damaged by misguided home improvements or botched repairs using the wrong materials. Even newly refurbished properties can sometimes conceal dangerous structural alterations and shoddy build-quality. This unique manual provides detailed, expert advice, backed up with clear how to colour photographs, describing where to check for the critical danger signs and how to fix all common defects. Home ExtensionMany people are looking at ways to extend their homes rather than move house, but `getting the builders in' can be a recipe for disaster unless you really know what you are doing. Whether you plan to employ a building contractor or tackle some of the works yourself, this best-selling manual will show you how to stay firmly in control, resulting in a high-quality extension, completed on time and within budget. This new edition will include all the up-do-date information on complying with the latest Building Regs and Planning requirements, CAD design, energy-efficiency, under floor heating, bi-folds, liquid screeds, woodburning stoves and renewable energy. Period Property Britain has a wonderfully rich stock of period houses - everything from medieval cottages to Georgian townhouses and Edwardian mansions. But many of these historic properties are now at risk. Some are unwittingly damaged by well-meaning owners or incompetent builders; others suffer long-term deterioration where mortgage lenders have imposed quick-fix 'remedies'. Despite being some of the most sustainable buildings on the planet, many old houses are now being subjected to ill-advised works to upgrade thermal efficiency, resulting in the destruction of the very qualities that make them so appealing, slashing their values. Haynes have come to the rescue with this clearly written, lavishly illustrated manual explaining the correct approach to care and repair - covering the full range of traditional materials. Every old house has a story to tell, so Haynes also show how to explore your home's history and strip back modern finishes to reveal long lost original features. This comprehensive manual is essential reading whether you want to get your hands dirty or just want to understand how old houses work and how to go about employing specialist craftsmen.24,99 £*Shipping: 2,99 £Secure redirect to the provider
-
NARS Sparked Liquid Eyeshadow liquid glitter eyeshadow shade HOT PROPERTY 3.5 mlNARS Sparked Liquid Eyeshadow, 3.5 ml, Eyeshadows for Women, Do you tend to hit the same few shades in your favourite eyeshadow palette but you just can’t do without them? Or are you travelling and can only fit the essentials in your toiletry bag? Thanks to its compact size, the NARS Sparked Liquid Eyeshadow eyeshadow won’t take up much room, so you can always have it on hand, be it by itself in your purse or as an accessory to your favourite palette. This allows you to give your lids a pop of colour or define the shape of your eyes to your liking, giving every makeup look a new dimension, no matter what your reason for getting them is. The formula ensures even pigment coverage, easy application and seamless blending without unwanted harsh transitions. Characteristics: long-lasting do not smudge in the crease of the eyelid washes out easily sparkling effect ophthalmologically tested30,80 £*Shipping: 3,99 £Secure redirect to the provider
-
J H Haynes & Co Ltd Haynes Period Property Manual: Care And Repair Of Old HousesHaynes Period Property Manual: Care And Repair Of Old Houses Britain has a wonderfully rich stock of period houses - everything from medieval cottages to Georgian townhouses and Edwardian mansions. But many of these historic properties are now at risk. Some are unwittingly damaged by well-meaning owners or incompetent builders; others suffer long-term deterioration where mortgage lenders have imposed quick-fix 'remedies'. Despite being some of the most sustainable buildings on the planet; many old houses are now being subjected to ill-advised works to upgrade thermal efficiency; resulting in the destruction of the very qualities that make them so appealing; slashing their values. Haynes have come to the rescue with this clearly written; lavishly illustrated manual explaining the correct approach to care and repair - covering the full range of traditional materials.10,99 £*Shipping: 2,99 £Secure redirect to the provider
-
What are transitory assets and/or liabilities?
Transitory assets and/or liabilities are items on a company's balance sheet that are expected to be settled or used up within a relatively short period of time, typically within one year. These items are considered to be temporary in nature and are not expected to have a long-term impact on the company's financial position. Examples of transitory assets include cash, accounts receivable, and inventory, while examples of transitory liabilities include accounts payable and short-term debt. It is important for investors and analysts to understand the nature of these transitory items when evaluating a company's financial health and performance. **
-
How are the assets and liabilities evaluated?
Assets and liabilities are evaluated based on their current market value or book value. For assets, this means determining their fair market value, which is the price that they could be sold for in the current market. Liabilities are evaluated based on their current outstanding balance or the amount that is owed. This evaluation helps to determine the financial health and position of a company, as well as its ability to meet its financial obligations. **
-
What is a statement of assets and liabilities?
A statement of assets and liabilities is a financial document that provides a snapshot of an individual's or organization's financial position at a specific point in time. It lists all the assets, such as cash, investments, property, and equipment, as well as all the liabilities, such as loans, mortgages, and other debts. The statement helps to assess the overall financial health and solvency of the entity by comparing the total assets to the total liabilities. It is an essential tool for financial planning, decision-making, and assessing the ability to meet financial obligations. **
-
How can accounting, liabilities, and receivables be interconnected?
Accounting, liabilities, and receivables are interconnected in the sense that they all play a role in a company's financial health. Liabilities are debts or obligations that a company owes, which are recorded on the balance sheet as part of the accounting process. Receivables, on the other hand, represent money owed to the company by its customers or clients, and are also recorded on the balance sheet as assets. The relationship between these two is that receivables can eventually become liabilities if they are not collected in a timely manner, which can impact the company's financial position. Therefore, proper accounting practices are essential to accurately track and manage both liabilities and receivables to ensure the company's financial stability. **
Similar search terms for Property
-
Quercus Financial Joy: Set your financial goals for 2026 - Banish Debt, Grow Your Money and Unlock Financial Freedom by Ken and Mary OkoroaforAs seen on ITV's This Morning! A life-changing 10-week plan to help you to turn your life around and design a path to financial freedom, enriched with the small experiences that bring you joy. Stop worrying about money. Start enjoying your life. You might be struggling in debt, living paycheque to paycheque, or worried about preparing for retirement; maybe you're considering your first investment, or you just want an escape plan from the '9 to 5'. Wherever you are on your journey, this book will revolutionize your lifestyle and your relationship with money. Authors Ken and Mary Okoroafor started out as resource-poor, working-class immigrants and have built a life of financial independence and joyful moments through hard work, smart saving and savvy investing. They know what it feels like to start from ground zero, and as a chartered accountant and former CFO, Ken shares his financial expertise to help you unlock the secret to building wealth. You'll learn how to take control of your finances, develop good money habits, become debt-free, invest in assets and multiply your income so you can create the freedom to travel, spend time with your loved ones and plan for a stress-free (early) retirement - all whilst prioritising your wellbeing and having fun! It also includes a dozen real-life interviews with singles, couples and those with children, from different backgrounds, age groups and stages of their money journey, including a few well-known public figures. Financial joy can be achieved by anyone - and it can start today, not tomorrow.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
HP 12c Platinum Financial Calculator (F2231AA)HP 12c Platinum Financial Calculator; Box includes Calculator, batteries, user manual, pouch. Display Description: 10 x 7-segment, single line. Built-in Functions: over 130. Character Display Maximum: 10. Entry System Logic: RPN; Algebraic. Graph Display Features: adjustable contrastA time-tested performer, the HP 12c has an easy-to-use layout, one-line LCD display and efficient RPN data entry. Easily calculate loan payments, interest rates and conversions, standard deviation, percent, TVM, NPV, IRR, cash flows, bonds and more. Over 120 built in functions.- Customizing Features.- Keystroke programming Memory capacity: 399 steps.- Time and Date Management.- Date arithmetic.- The Time-Tested Performer.- Business/Financial Features Statistical/Mathematical Features, Time and Date Management, and Customizing Features, Attractive one line x 10-character LCD display, Select business functions at your fingertips, Great mix of statistic, business and math functions, Read display results easily, even at an angle.- Business/Financial Features.- TVM (loans, savings, and leasing) Amortization Bond price and yield to maturity Cash flow analysis NPV, IRR Memory for up to 20 cash flows SL, DB, SOYD depreciation methods % change, % of total.- Statistical/Mathematical Features.- Cumulative statistical analysis Std. deviation, mean, weighted mean Linear regression Forecasting, correlation coefficient Total, £x, £x2, £y, £y2, £xy +, -, x, %, ÷, 1/x, ±, LN, ex, n!.- Ideal for.- Real estate, finance, accounting, economics and business work. Permitted for use on the CFP and CFA Certification Exams, and GARP FRM Exam.40,99 £*Shipping: 0,00 £Secure redirect to the provider
-
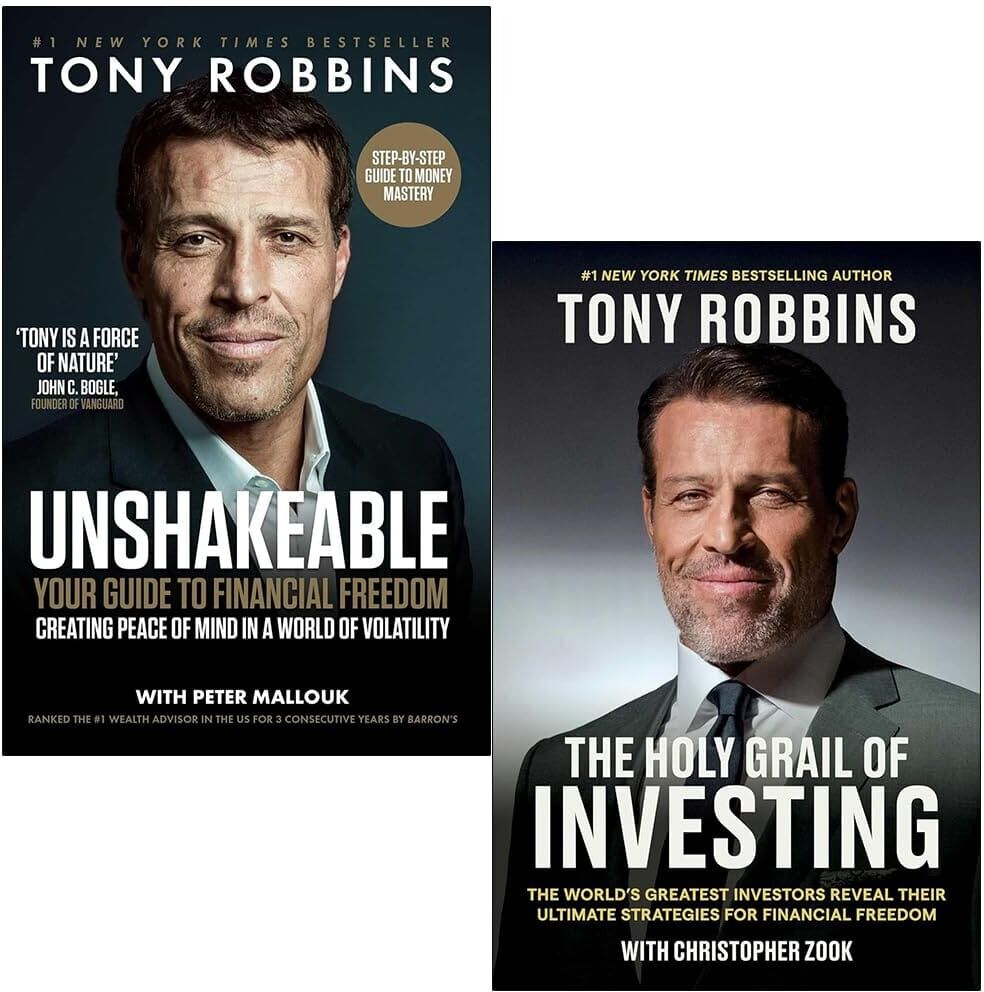
Financial Freedom Collection By Tony Robbins 2 Books Set - Non Fiction - Paperback Simon & SchusterTitles in this set: 1. Unshakeable: Your Guide to Financial Freedom 2. The Holy Grail of Investing Description: Unshakeable: Your Guide to Financial Freedom Tony Robbins, arguably the most recognizable life and business strategist and guru, is back with a timely, unique follow-up. Market corrections are as constant as seasons are in nature. There have been 30 such corrections in the past 30 years, yet there’s never been an action plan for how not only to survive, but thrive through each change in the stock market. Building upon the principles in Money: Master the Game, Robbins offers the reader specific steps they can implement to protect their investments while maximizing their wealth. It’s a detailed guide designed for investors, articulated in the common-sense, practical manner that the millions of loyal Robbins fans and students have come to expect and rely upon. Few have navigated the turbulence of the stock market as adeptly and successfully as Tony Robbins. His proven, consistent success over decades makes him singularly qualified to help investors (both seasoned and first-timers alike) preserve and add to their investments. The Holy Grail of Investing In this new book, Tony Robbins teams up with Christopher Zook, a renowned financial investor . Together they reveal how, for decades, trillions of dollars of smart money – think of large institutions, sovereign wealth funds, individuals with ultra-high-net worth – have been making outsized returns using alternative investments in private equity, private credit, private real estate, energy and venture capital. Until recently, the vast majority of investors – those of us without insider access or eye-popping checkbooks – have been locked out of these exciting, high-yield opportunities. But there is a change underway. Alternative investments are coming to the masses, and investors need to know how to navigate their options, assess the merits of these opportunities, and determine how to best take advantage of this massive trend. In The Holy Grain of Investing , you’ll discover: Where opportunities will arise as we transition from the 'free money' era of zero interest rates to a new more realistic environment. How to take advantage of the trillions flowing into private investments by owning a piece of the firms that manage the assets. How to take advantage of private credit as an alternative (or compliment) to bonds. How and why professional sports teams have become an asset class of their own. How the renewable energy revolution will create new winners and losers. How investments in private real estate can work as an inflationary hedge. Interviews, advice, and insights from some of the world’s most formidable titans of industry, such as Howard Marks of OakTree Capital, Vinod Khosla of Khosla Capital, Barry Sternlicht of Starwood, Robert Smith of Vista, and Peter Theil of Founders Fund, among others. The market is changing, and the conventional wisdom no longer applies. Are you ready to add some...18,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Why must the assets and liabilities be equal in size?
The assets and liabilities must be equal in size because they represent the financial position of a company at a specific point in time. If the assets exceed the liabilities, it may indicate that the company has more resources than it owes, which could be a positive sign of financial health. On the other hand, if the liabilities exceed the assets, it may indicate that the company has more obligations than resources, which could be a sign of financial risk. Therefore, having equal-sized assets and liabilities provides a balanced and accurate representation of the company's financial standing. **
-
What are bank liabilities and bank balances in accounting?
In accounting, bank liabilities refer to the obligations that a bank owes to its customers and other financial institutions. This includes deposits made by customers, such as savings accounts, checking accounts, and certificates of deposit. Bank balances, on the other hand, represent the amount of money that a bank holds in its accounts, including cash reserves and funds deposited with other banks. These balances are crucial for a bank's liquidity and ability to meet its financial obligations. **
-
How does rainwater from the neighboring property reach our property?
Rainwater from the neighboring property reaches our property through natural drainage patterns and the force of gravity. It may flow downhill or through the soil, eventually reaching our property boundaries. The topography of the land, such as slopes or depressions, can also influence the direction and flow of rainwater towards our property. Additionally, man-made structures like gutters, downspouts, or drainage systems on the neighboring property can direct rainwater towards our property. **
-
Should property owners have more responsibility for their own property?
Yes, property owners should have more responsibility for their own property. They should be accountable for maintaining their property to ensure the safety and well-being of others. This includes regular maintenance, repairs, and ensuring that their property meets all safety standards. By taking on more responsibility, property owners can contribute to creating a safer and more pleasant environment for everyone. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.