Buy bilanzierung.eu ?
We are moving the project
bilanzierung.eu .
Are you interested in purchasing the domain
bilanzierung.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy bilanzierung.eu ?
What are transitory assets and/or liabilities?
Transitory assets and/or liabilities are items on a company's balance sheet that are expected to be settled or used up within a relatively short period of time, typically within one year. These items are considered to be temporary in nature and are not expected to have a long-term impact on the company's financial position. Examples of transitory assets include cash, accounts receivable, and inventory, while examples of transitory liabilities include accounts payable and short-term debt. It is important for investors and analysts to understand the nature of these transitory items when evaluating a company's financial health and performance. **
How are the assets and liabilities evaluated?
Assets and liabilities are evaluated based on their current market value or book value. For assets, this means determining their fair market value, which is the price that they could be sold for in the current market. Liabilities are evaluated based on their current outstanding balance or the amount that is owed. This evaluation helps to determine the financial health and position of a company, as well as its ability to meet its financial obligations. **
Similar search terms for Poor
Top-Angebote
Products related to Poor:
-
HH Rich Dad Poor Dad, Atomic Habits, The Psychology of Money 3 Books Collection SetRich Dad Poor Dad, Atomic Habits, The Psychology of Money 3 Books Collection Set by Robert T. Kiyosaki, James Clear, Morgan Housel Titles in This Set: Rich Dad Poor Dad : What the Rich Teach Their Kids About Money That the Poor and Middle Class Do Not! Rich Dad Poor Dad consistently ranks among bestsellers around the world in the categories of Personal Finance, Parenting, and Investing, has been translated into 38 languages, and has sold more than 40 million copies worldwide. Rich Dad Poor Dad is Robert's story of growing up with two dads -his real father and the father of his best friend, his rich dad - and the waysin which both men shaped his thoughts about money and investing. The bookexplodes the myth that you need to earn a high income to be rich and explainsthe difference between working for money and having your money work for you. Atomic Habits : the life-changing million-copy #1 bestseller THE PHENOMENAL INTERNATIONAL BESTSELLER: OVER 1O MILLION COPIES SOLD WORLDWIDETransform your life with tiny changes in behaviour, starting now. People think that when you want to change your life, you need to think big. But world-renowned habits expert James Clear has discovered another way. He knows that real change comes from the compound effect of hundreds of small decisions: doing two push-ups a day, waking up five minutes early, or holding a single short phone call. He calls them atomic habits. In this ground-breaking book, Clears reveals exactly how these minuscule changes can grow into such life-altering outcomes. The Psychology of Money : Timeless lessons on wealth, greed, and happiness Doing well with money isn't necessarily about what you know. It's about how you behave. And behavior is hard to teach, even to really smart people. Money-investing, personal finance, and business decisions-is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet. They make them at the dinner table, or in a meeting room, where personal history, your own unique view of the world, ego, pride, marketing, and odd incentives are scrambled together. In The Psychology of Money, award-winning author Morgan Housel shares 19 short stories exploring the strange ways people think about money and teaches you how to make better sense of one of life's most important topics.24,99 £*Shipping: 2,99 £Secure redirect to the provider
-
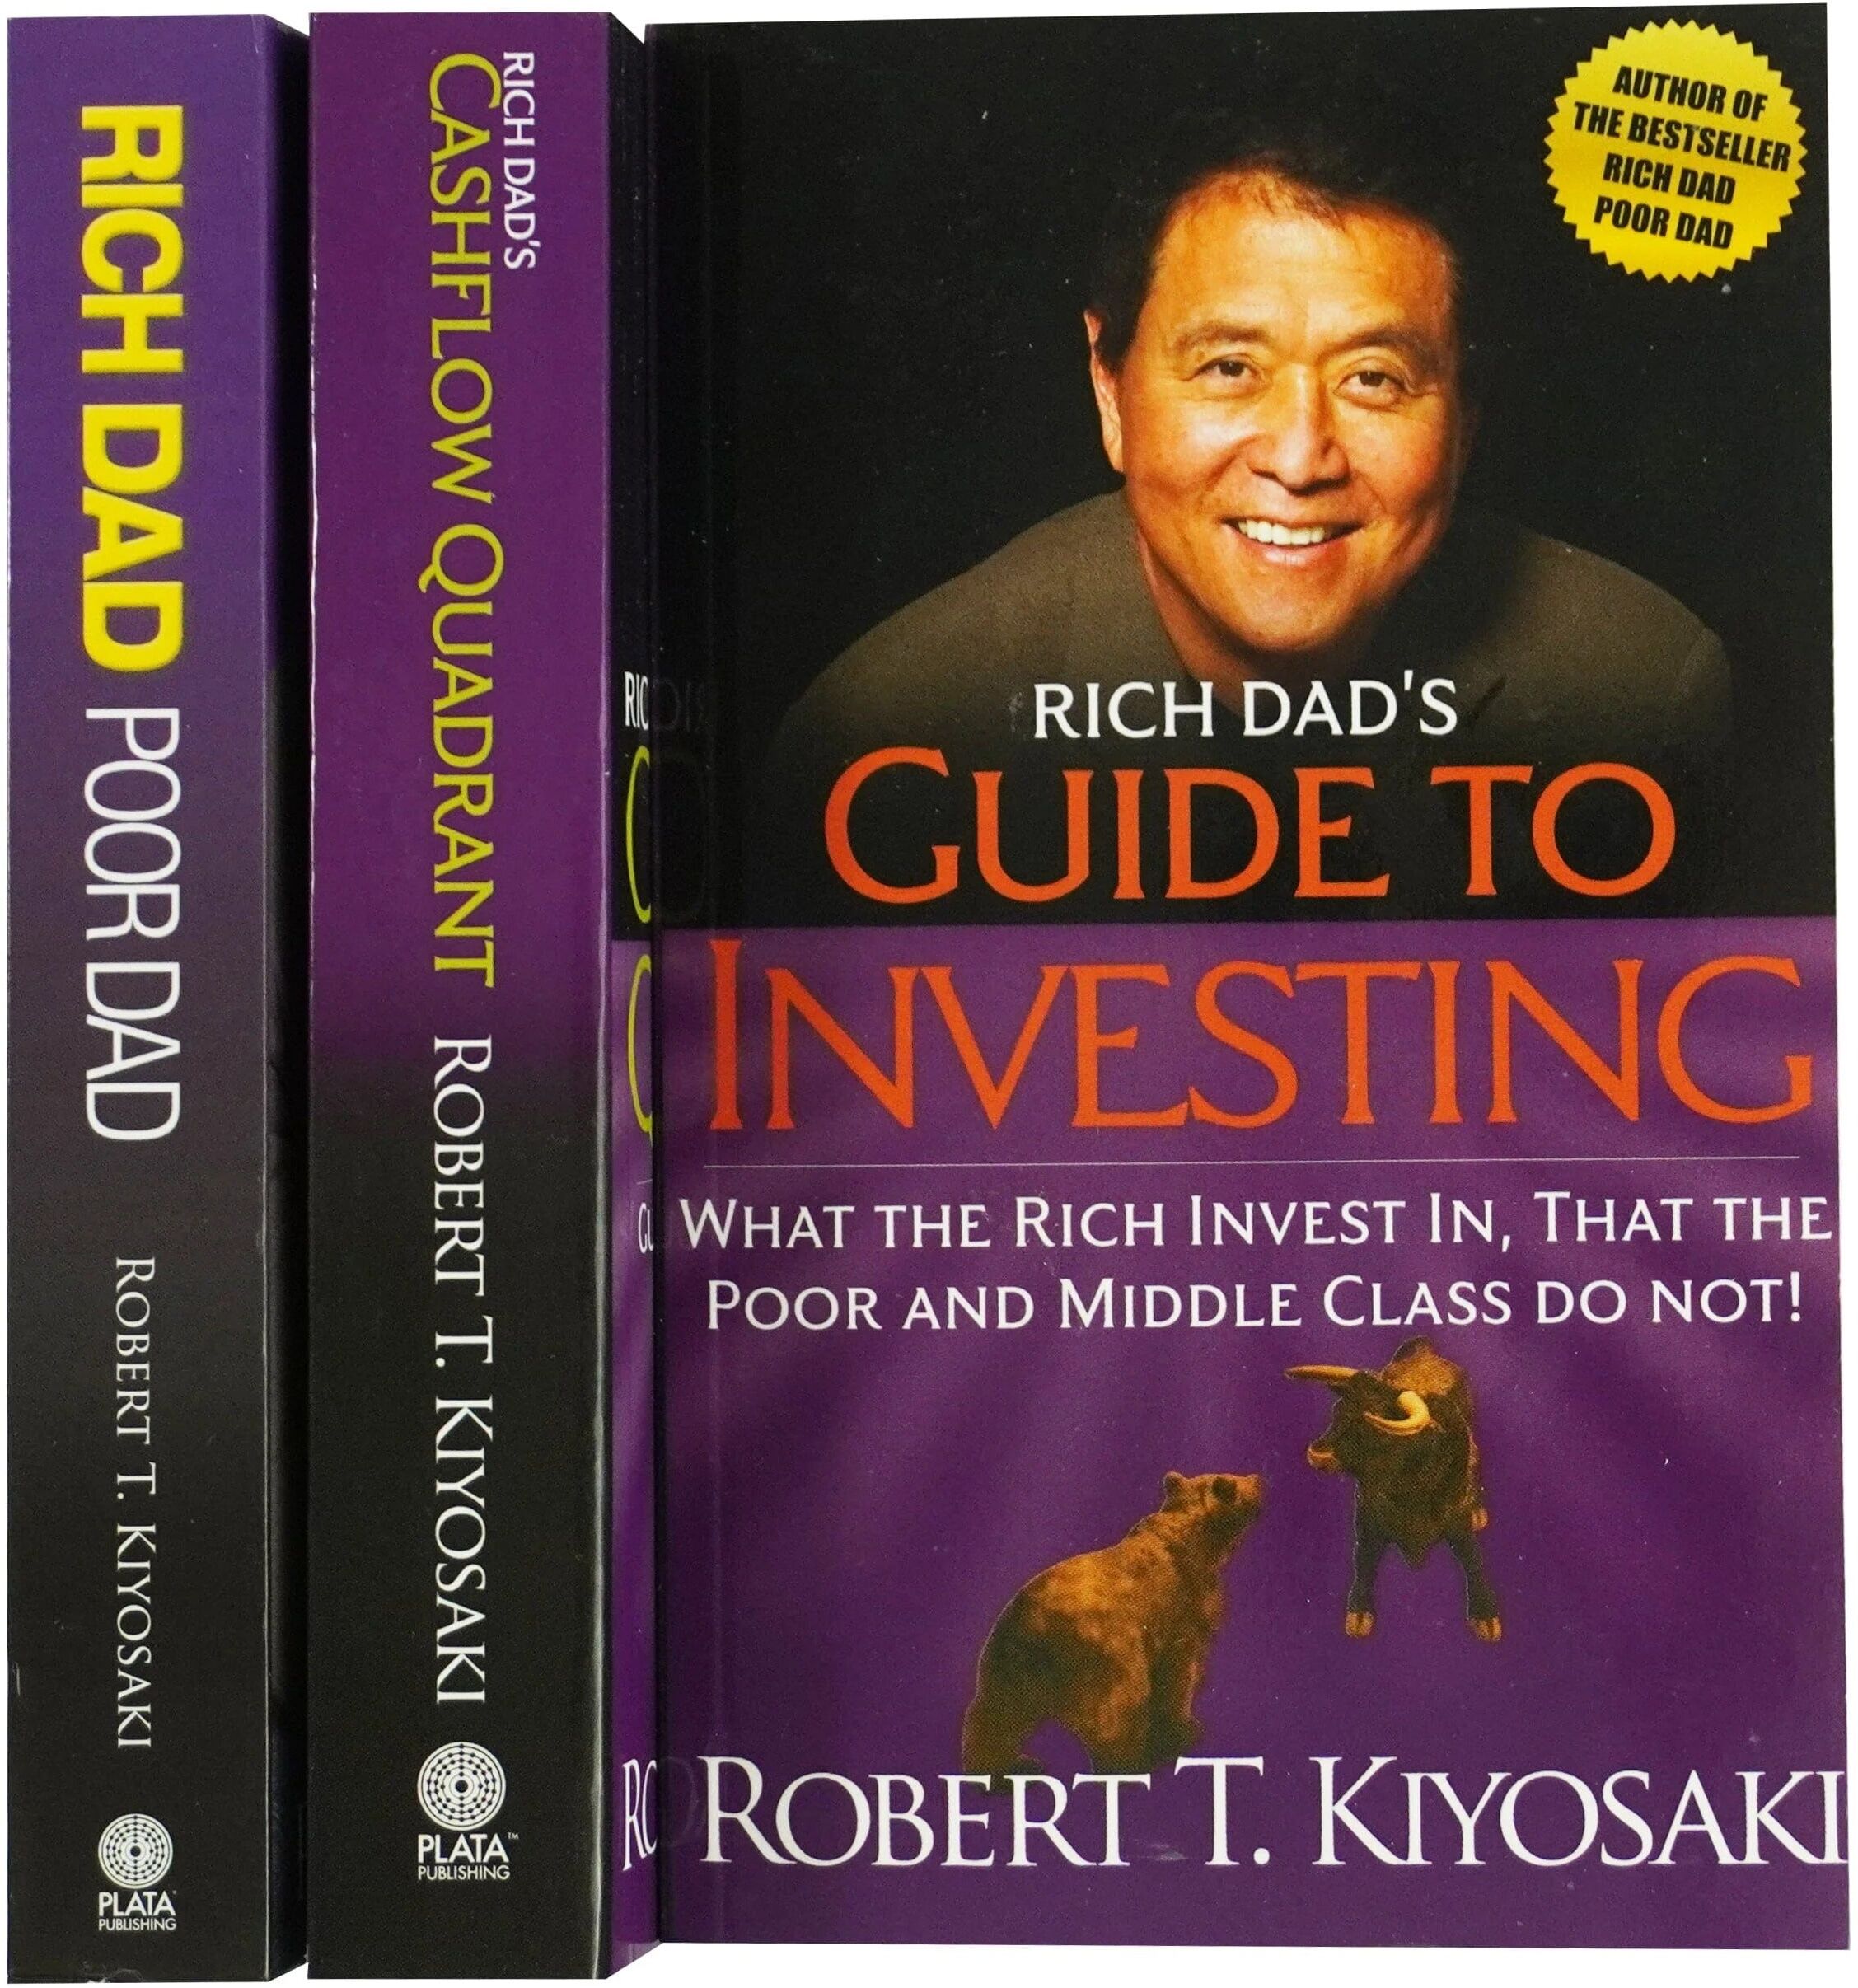
Rich Dad Poor Dad Robert T. Kiyosaki 3 Books Collection Set - Non Fiction - Paperback Plata PublishingTitle in This Set: Rich Dad's Cashflow Quadrant Rich Dad's Guide to Investing Rich Dad Poor Dad Description Robert T. Kiyosaki is one of the most influential voices in personal finance, known for challenging traditional ideas about money, work and wealth. This three-book collection brings together his most impactful titles — Rich Dad Poor Dad, Rich Dad’s Guide to Investing and Rich Dad’s Cashflow Quadrant — offering a practical and accessible roadmap to financial independence. First published in 1997, Rich Dad Poor Dad has become a global phenomenon, helping millions rethink how they view money. Through the contrast between his “poor dad” and his “rich dad,” Kiyosaki introduces the fundamentals of financial literacy, explains the difference between assets and liabilities, and encourages readers to build income streams that work for them — not the other way around. Rich Dad’s Guide to Investing takes these ideas further, offering deeper insight into real-world investing. Focusing on real estate, stocks and business ownership, the book explains how experienced investors assess opportunities, manage risk and build long-term wealth through informed decision-making. In Rich Dad’s Cashflow Quadrant, Kiyosaki explores the four main ways people earn income — employee, self-employed, business owner and investor. By breaking down the mindset and skills needed for each quadrant, he shows readers how to move toward the right-hand side of the quadrant, where financial freedom and passive income are built. Together, these books form a powerful foundation for anyone looking to take control of their finances, improve their money mindset and create a more secure financial future. Whether you’re new to personal finance or ready to deepen your investing knowledge, this Robert T. Kiyosaki collection is an essential addition to your bookshelf — available at great value from Books2Door.12,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing/Wilco/RANDOM HOUSE Think and Grow Rich, Rich Dad Poor Dad and Atomic Habits 3 Books Collection SetThink and Grow Rich, Rich Dad Poor Dad and Atomic Habits 3 Books Collection Set By: James Clear, Napoleon Hill and Robert T. Kiyosaki Title In This Set: Atomic Habits: The life-changing by James Clear million copy bestseller Transform your life with tiny changes in behaviour, starting now. People think that when you want to change your life, you need to think big. But world-renowned habits expert James Clear has discovered another way. Rich Dad Poor Dad: What the Rich Teach Their Kids About Money That the Poor and Middle Class Do Not! Rich Dad Poor Dad is Robert's story of growing up with two dads — his real father and the father of his best friend, his rich dad — and the ways in which both men shaped his thoughts about money and investing. The book explodes the myth that you need to earn a high income to be rich and explains the difference between working for money and having your money work for you. Think And Grow Rich Napoleon Hill, America's most beloved motivational author, devoted 25 years to finding out how the wealthy became that way. After interviewing over 500 of the most affluent men and women of his time, he uncovered the secret to great wealth based on the notion that if we can learn to think like the rich, we can start to behave like them. By understanding and applying the thirteen simple steps that constitute Hill's formula, you can achieve your goals, change your life and join the ranks of the rich and successful. In this updated edition, Dr. Arthur R. Pell provides examples of men and women who, in recent times, exemplify the principles that Hill promulgated. With the success stories of top achievers such as Bill Gates and Steven Spielberg, he proves that Hill's philosophies are as valid today as they ever were.14,89 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing Robert T. Kiyosaki Classics 3 Books Collection Box Set (Rich Dad Poor Dad, Cashflow Quadrant, Guide to Investing)Rich Dads Guide To Investing Investing means different things to different people… and there is a huge difference between passive investing and becoming an active, engaged investor. Rich Dad’s Guide to Investing, one of the three core titles in the Rich Dad Series, covers the basic rules of investing, how to reduce your investment risk, how to convert your earned income into passive income… plus Rich Dad’s 10 Investor Controls. Rich Dads Cashflow Quadrant Tired of living paycheck to paycheck? Learn why some people work less but earn more. Pay less in taxes, and learn to make their money work for them. It's simply knowing which quadrant to work from ― and when. The wealthy know that the keys to wealth and financial freedom are found on the right side of the quadrant, through business and investing. Rich Dad Poor Dad Rich Dad Poor Dad is Robert's story of growing up with two dads — his real father and the father of his best friend, his rich dad — and the ways in which both men shaped his thoughts about money and investing. The book explodes the myth that you need to earn a high income to be rich and explains the difference between working for money and having your money work for you. In many ways, the messages of Rich Dad Poor Dad, messages that were challenged and criticized 25 ago, are more meaningful, relevant, and important today than ever.11,89 £*Shipping: 2,99 £Secure redirect to the provider


-
What is a statement of assets and liabilities?
A statement of assets and liabilities is a financial document that provides a snapshot of an individual's or organization's financial position at a specific point in time. It lists all the assets, such as cash, investments, property, and equipment, as well as all the liabilities, such as loans, mortgages, and other debts. The statement helps to assess the overall financial health and solvency of the entity by comparing the total assets to the total liabilities. It is an essential tool for financial planning, decision-making, and assessing the ability to meet financial obligations. **
-
Why do people in poor countries have children despite their poor financial situation, while people in the West do not have children due to their poor financial situation?
People in poor countries often have children despite their financial situation because children are seen as a form of social security and support in old age. In many developing countries, children are expected to take care of their parents in their old age and provide support for the family. On the other hand, in the West, the cost of raising children is very high, and there are social safety nets in place for the elderly, such as pensions and healthcare, which reduce the need for children to provide financial support. Additionally, in the West, there is a greater emphasis on individualism and personal fulfillment, which can lead people to delay or forgo having children if they feel they cannot provide for them financially. **
-
From what net income is one considered poor?
One is considered poor if their net income falls below the poverty line, which is determined by the government and varies depending on factors such as household size and location. The poverty line is set at a level that is considered to be the minimum income required to meet basic needs such as food, shelter, and clothing. If an individual or household's net income falls below this threshold, they are considered to be living in poverty. **
-
How can accounting, liabilities, and receivables be interconnected?
Accounting, liabilities, and receivables are interconnected in the sense that they all play a role in a company's financial health. Liabilities are debts or obligations that a company owes, which are recorded on the balance sheet as part of the accounting process. Receivables, on the other hand, represent money owed to the company by its customers or clients, and are also recorded on the balance sheet as assets. The relationship between these two is that receivables can eventually become liabilities if they are not collected in a timely manner, which can impact the company's financial position. Therefore, proper accounting practices are essential to accurately track and manage both liabilities and receivables to ensure the company's financial stability. **
Is a net income of 1700 euros considered poor?
A net income of 1700 euros per month would be considered poor in many European countries, especially in more expensive cities or regions. This amount may not be enough to cover basic living expenses such as housing, food, utilities, and healthcare, leaving little room for savings or discretionary spending. Additionally, the poverty line varies by country and depends on factors such as cost of living, household size, and social welfare programs. Therefore, while 1700 euros may not be considered poor in some regions, it would likely be below the poverty line in others. **
Why must the assets and liabilities be equal in size?
The assets and liabilities must be equal in size because they represent the financial position of a company at a specific point in time. If the assets exceed the liabilities, it may indicate that the company has more resources than it owes, which could be a positive sign of financial health. On the other hand, if the liabilities exceed the assets, it may indicate that the company has more obligations than resources, which could be a sign of financial risk. Therefore, having equal-sized assets and liabilities provides a balanced and accurate representation of the company's financial standing. **
Top-Angebote
Products related to Poor:
-
Plata Publishing FAKE: Fake Money, Fake Teachers, Fake Assets & Rich Dad Poor Dad By Robert T. Kiyosaki 2 Books Collection SetFAKE: Fake Money, Fake Teachers, Fake Assets & Rich Dad Poor Dad By Robert T. Kiyosaki 2 Books Collection Set: FAKE: Fake Money, Fake Teachers, Fake Assets: In FAKE: Fake Money, Fake Teachers, Fake Assets, Robert delivers insights and answers that help ordinary people―who probably haven’t had a lot of financial education―determine what’s ‘real’ and relevant to their financial lives. Every day we are bombarded with news reports and information and opinions… How do we decipher fact from fiction? How do we differentiate between truth and lies? And determine what’s real… from what isn’t? Kiyosaki believes that it starts with education, financial education designed to make us smarter with our money―and able to fight what’s fake and use what isn’t to secure our financial future. Rich Dad Poor Dad: Rich Dad Poor Dad is Robert's story of growing up with two dads — his real father and the father of his best friend, his rich dad — and the ways in which both men shaped his thoughts about money and investing. The book explodes the myth that you need to earn a high income to be rich and explains the difference between working for money and having your money work for you.12,95 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing Rich Dad Poor Dad What The Rich Teach Their Kids About Money That The Poor And Middle Class Do NotApril of 2022 marks a 25-year milestone for the personal finance classic Rich Dad Poor Dad that still ranks as the #1 Personal Finance book of all time. And although 25 years have passed since Rich Dad Poor Dad was first published, readers will find that very little in the book itself has changed — and for good reason. While so much in our world is changing a high speed, the lessons about money and the principles of Rich Dad Poor Dad haven’t changed. Today, as money continues to play a key role in our daily lives, the messages in Robert Kiyosaki’s international bestseller are more timely and more important than ever. Milestones While there is a milestone to commemorate — and a new section in the book on Why Milestones Are Important — preserving the integrity of the original content is testimony to the fact that this book has truly stood the test of time. The sidebars throughout the book (that were updated for the 20-year anniversary edition) have been updated again, but the core principles that parents and grandparents — those who embraced Robert’s story and messages 25 years ago — are sharing them with new generations who have found that its timeless wisdom and no-nonsense lessons can be applied to anyone’s life and their vision for a future that includes taking control of their finances. People of all cultures and countries celebrate milestones. We use them to measure time, mark progress, reflect on the lessons we’ve learned, and celebrate accomplishments… and they give meaning to our life’s journey. They are a way that we integrate past, present, and future… looking back at where we started, where we are today… and the promise of all that the future can hold. In the quarter century that has passed since Rich Dad Poor Dad was first published — 25 years since April 8, 1997 — so many things in our world have changed. But the one thing that has not changed is the pressing need for and the power of financial education. Money is still a mainstay of our lives, like it or not, and technology has brought both speed and innovations to the world of money. In an ever-changing world, we can all still get smarter when it comes to money… and learn as much as we can to secure our future. Still the One… #1 Today Rich Dad Poor Dad consistently ranks among bestsellers around the world in the categories of Personal Finance, Parenting, and Investing, has been translated into 38 languages, and has sold more than 40 million copies worldwide. Rich Dad Poor Dad is Robert's story of growing up with two dads — his real father and the father of his best friend, his rich dad — and the ways in which both men shaped his thoughts about money and investing. The book explodes the myth that you need to earn a high income to be rich and explains the difference between working for money and having your money work for you. In many ways, the messages of Rich Dad Poor Dad, messages that were challenged and criticized 25 ago, are more meaningful, relevant, and important today than...5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
HH Rich Dad Poor Dad, Atomic Habits, The Psychology of Money 3 Books Collection SetRich Dad Poor Dad, Atomic Habits, The Psychology of Money 3 Books Collection Set by Robert T. Kiyosaki, James Clear, Morgan Housel Titles in This Set: Rich Dad Poor Dad : What the Rich Teach Their Kids About Money That the Poor and Middle Class Do Not! Rich Dad Poor Dad consistently ranks among bestsellers around the world in the categories of Personal Finance, Parenting, and Investing, has been translated into 38 languages, and has sold more than 40 million copies worldwide. Rich Dad Poor Dad is Robert's story of growing up with two dads -his real father and the father of his best friend, his rich dad - and the waysin which both men shaped his thoughts about money and investing. The bookexplodes the myth that you need to earn a high income to be rich and explainsthe difference between working for money and having your money work for you. Atomic Habits : the life-changing million-copy #1 bestseller THE PHENOMENAL INTERNATIONAL BESTSELLER: OVER 1O MILLION COPIES SOLD WORLDWIDETransform your life with tiny changes in behaviour, starting now. People think that when you want to change your life, you need to think big. But world-renowned habits expert James Clear has discovered another way. He knows that real change comes from the compound effect of hundreds of small decisions: doing two push-ups a day, waking up five minutes early, or holding a single short phone call. He calls them atomic habits. In this ground-breaking book, Clears reveals exactly how these minuscule changes can grow into such life-altering outcomes. The Psychology of Money : Timeless lessons on wealth, greed, and happiness Doing well with money isn't necessarily about what you know. It's about how you behave. And behavior is hard to teach, even to really smart people. Money-investing, personal finance, and business decisions-is typically taught as a math-based field, where data and formulas tell us exactly what to do. But in the real world people don't make financial decisions on a spreadsheet. They make them at the dinner table, or in a meeting room, where personal history, your own unique view of the world, ego, pride, marketing, and odd incentives are scrambled together. In The Psychology of Money, award-winning author Morgan Housel shares 19 short stories exploring the strange ways people think about money and teaches you how to make better sense of one of life's most important topics.24,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Rich Dad Poor Dad Robert T. Kiyosaki 3 Books Collection Set - Non Fiction - Paperback Plata PublishingTitle in This Set: Rich Dad's Cashflow Quadrant Rich Dad's Guide to Investing Rich Dad Poor Dad Description Robert T. Kiyosaki is one of the most influential voices in personal finance, known for challenging traditional ideas about money, work and wealth. This three-book collection brings together his most impactful titles — Rich Dad Poor Dad, Rich Dad’s Guide to Investing and Rich Dad’s Cashflow Quadrant — offering a practical and accessible roadmap to financial independence. First published in 1997, Rich Dad Poor Dad has become a global phenomenon, helping millions rethink how they view money. Through the contrast between his “poor dad” and his “rich dad,” Kiyosaki introduces the fundamentals of financial literacy, explains the difference between assets and liabilities, and encourages readers to build income streams that work for them — not the other way around. Rich Dad’s Guide to Investing takes these ideas further, offering deeper insight into real-world investing. Focusing on real estate, stocks and business ownership, the book explains how experienced investors assess opportunities, manage risk and build long-term wealth through informed decision-making. In Rich Dad’s Cashflow Quadrant, Kiyosaki explores the four main ways people earn income — employee, self-employed, business owner and investor. By breaking down the mindset and skills needed for each quadrant, he shows readers how to move toward the right-hand side of the quadrant, where financial freedom and passive income are built. Together, these books form a powerful foundation for anyone looking to take control of their finances, improve their money mindset and create a more secure financial future. Whether you’re new to personal finance or ready to deepen your investing knowledge, this Robert T. Kiyosaki collection is an essential addition to your bookshelf — available at great value from Books2Door.12,99 £*Shipping: 2,99 £Secure redirect to the provider
-
What are transitory assets and/or liabilities?
Transitory assets and/or liabilities are items on a company's balance sheet that are expected to be settled or used up within a relatively short period of time, typically within one year. These items are considered to be temporary in nature and are not expected to have a long-term impact on the company's financial position. Examples of transitory assets include cash, accounts receivable, and inventory, while examples of transitory liabilities include accounts payable and short-term debt. It is important for investors and analysts to understand the nature of these transitory items when evaluating a company's financial health and performance. **
-
How are the assets and liabilities evaluated?
Assets and liabilities are evaluated based on their current market value or book value. For assets, this means determining their fair market value, which is the price that they could be sold for in the current market. Liabilities are evaluated based on their current outstanding balance or the amount that is owed. This evaluation helps to determine the financial health and position of a company, as well as its ability to meet its financial obligations. **
-
What is a statement of assets and liabilities?
A statement of assets and liabilities is a financial document that provides a snapshot of an individual's or organization's financial position at a specific point in time. It lists all the assets, such as cash, investments, property, and equipment, as well as all the liabilities, such as loans, mortgages, and other debts. The statement helps to assess the overall financial health and solvency of the entity by comparing the total assets to the total liabilities. It is an essential tool for financial planning, decision-making, and assessing the ability to meet financial obligations. **
-
Why do people in poor countries have children despite their poor financial situation, while people in the West do not have children due to their poor financial situation?
People in poor countries often have children despite their financial situation because children are seen as a form of social security and support in old age. In many developing countries, children are expected to take care of their parents in their old age and provide support for the family. On the other hand, in the West, the cost of raising children is very high, and there are social safety nets in place for the elderly, such as pensions and healthcare, which reduce the need for children to provide financial support. Additionally, in the West, there is a greater emphasis on individualism and personal fulfillment, which can lead people to delay or forgo having children if they feel they cannot provide for them financially. **
Similar search terms for Poor
-
Plata Publishing/Wilco/RANDOM HOUSE Think and Grow Rich, Rich Dad Poor Dad and Atomic Habits 3 Books Collection SetThink and Grow Rich, Rich Dad Poor Dad and Atomic Habits 3 Books Collection Set By: James Clear, Napoleon Hill and Robert T. Kiyosaki Title In This Set: Atomic Habits: The life-changing by James Clear million copy bestseller Transform your life with tiny changes in behaviour, starting now. People think that when you want to change your life, you need to think big. But world-renowned habits expert James Clear has discovered another way. Rich Dad Poor Dad: What the Rich Teach Their Kids About Money That the Poor and Middle Class Do Not! Rich Dad Poor Dad is Robert's story of growing up with two dads — his real father and the father of his best friend, his rich dad — and the ways in which both men shaped his thoughts about money and investing. The book explodes the myth that you need to earn a high income to be rich and explains the difference between working for money and having your money work for you. Think And Grow Rich Napoleon Hill, America's most beloved motivational author, devoted 25 years to finding out how the wealthy became that way. After interviewing over 500 of the most affluent men and women of his time, he uncovered the secret to great wealth based on the notion that if we can learn to think like the rich, we can start to behave like them. By understanding and applying the thirteen simple steps that constitute Hill's formula, you can achieve your goals, change your life and join the ranks of the rich and successful. In this updated edition, Dr. Arthur R. Pell provides examples of men and women who, in recent times, exemplify the principles that Hill promulgated. With the success stories of top achievers such as Bill Gates and Steven Spielberg, he proves that Hill's philosophies are as valid today as they ever were.14,89 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing Robert T. Kiyosaki Classics 3 Books Collection Box Set (Rich Dad Poor Dad, Cashflow Quadrant, Guide to Investing)Rich Dads Guide To Investing Investing means different things to different people… and there is a huge difference between passive investing and becoming an active, engaged investor. Rich Dad’s Guide to Investing, one of the three core titles in the Rich Dad Series, covers the basic rules of investing, how to reduce your investment risk, how to convert your earned income into passive income… plus Rich Dad’s 10 Investor Controls. Rich Dads Cashflow Quadrant Tired of living paycheck to paycheck? Learn why some people work less but earn more. Pay less in taxes, and learn to make their money work for them. It's simply knowing which quadrant to work from ― and when. The wealthy know that the keys to wealth and financial freedom are found on the right side of the quadrant, through business and investing. Rich Dad Poor Dad Rich Dad Poor Dad is Robert's story of growing up with two dads — his real father and the father of his best friend, his rich dad — and the ways in which both men shaped his thoughts about money and investing. The book explodes the myth that you need to earn a high income to be rich and explains the difference between working for money and having your money work for you. In many ways, the messages of Rich Dad Poor Dad, messages that were challenged and criticized 25 ago, are more meaningful, relevant, and important today than ever.11,89 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing Rich Dad's Guide to Investing: What the Rich Invest in, That the Poor and the Middle Class Do Not!Learn how the wealthy think about money and investing with Rich Dad’s Guide to Investing by Robert T. Kiyosaki, bestselling author of Rich Dad Poor Dad. In this practical and eye-opening guide, Kiyosaki explains what the rich invest in—and why, revealing the mindset, strategies, and financial intelligence needed to build long-term wealth. Rather than focusing on quick profits, this book emphasizes financial education, asset-building, risk management, and cash-flow investing. Designed for aspiring investors at every level, the book breaks down complex financial concepts into clear, actionable lessons. Readers learn how to think like professional investors, understand different asset classes, and create a solid foundation for financial independence. What You’ll Learn: How rich investors think differently about money The difference between assets and liabilities How to reduce investment risk through education Why financial intelligence matters more than a high income Strategies for building wealth and long-term cash flow Whether you’re new to investing or looking to sharpen your financial mindset, Rich Dad’s Guide to Investing offers valuable insights for anyone serious about achieving financial freedom.4,99 £*Shipping: 1,99 £Secure redirect to the provider
-
Plata Publishing Robert T. Kiyosaki's Rich Dads Guide To Investing, Rich Dads Cashflow Quadrant, Rich Dad Poor Dad, 3 Books Collection SetRobert T. Kiyosaki 3 Books Set Rich Dads Guide To Investing, Rich Dads Cashflow Quadrant, Rich Dad Poor Dad Title In This Set: Rich Dads Guide To Investing, Richd Dads Cashflow Quadrant, Rich Dad Poor Dad Describtion: Rich Dads Guide To Investing: Investing means different things to different people… and there is a huge difference between passive investing and becoming an active, engaged investor. Rich Dad’s Guide to Investing, one of the three core titles in the Rich Dad Series, covers the basic rules of investing, how to reduce your investment risk, how to convert your earned income into passive income… plus Rich Dad’s 10 Investor Controls. Rich Dads Cashflow Quadrant: Tired of living paycheck to paycheck? Learn why some people work less but earn more. Pay less in taxes, and learn to make their money work for them. It's simply knowing which quadrant to work from ― and when. The wealthy know that the keys to wealth and financial freedom are found on the right side of the quadrant, through business and investing. Rich Dad Poor Dad: Rich Dad Poor Dad is Robert's story of growing up with two dads — his real father and the father of his best friend, his rich dad — and the ways in which both men shaped his thoughts about money and investing. The book explodes the myth that you need to earn a high income to be rich and explains the difference between working for money and having your money work for you. In many ways, the messages of Rich Dad Poor Dad, messages that were challenged and criticized 25 ago, are more meaningful, relevant, and important today than ever.12,99 £*Shipping: 2,99 £Secure redirect to the provider
-
From what net income is one considered poor?
One is considered poor if their net income falls below the poverty line, which is determined by the government and varies depending on factors such as household size and location. The poverty line is set at a level that is considered to be the minimum income required to meet basic needs such as food, shelter, and clothing. If an individual or household's net income falls below this threshold, they are considered to be living in poverty. **
-
How can accounting, liabilities, and receivables be interconnected?
Accounting, liabilities, and receivables are interconnected in the sense that they all play a role in a company's financial health. Liabilities are debts or obligations that a company owes, which are recorded on the balance sheet as part of the accounting process. Receivables, on the other hand, represent money owed to the company by its customers or clients, and are also recorded on the balance sheet as assets. The relationship between these two is that receivables can eventually become liabilities if they are not collected in a timely manner, which can impact the company's financial position. Therefore, proper accounting practices are essential to accurately track and manage both liabilities and receivables to ensure the company's financial stability. **
-
Is a net income of 1700 euros considered poor?
A net income of 1700 euros per month would be considered poor in many European countries, especially in more expensive cities or regions. This amount may not be enough to cover basic living expenses such as housing, food, utilities, and healthcare, leaving little room for savings or discretionary spending. Additionally, the poverty line varies by country and depends on factors such as cost of living, household size, and social welfare programs. Therefore, while 1700 euros may not be considered poor in some regions, it would likely be below the poverty line in others. **
-
Why must the assets and liabilities be equal in size?
The assets and liabilities must be equal in size because they represent the financial position of a company at a specific point in time. If the assets exceed the liabilities, it may indicate that the company has more resources than it owes, which could be a positive sign of financial health. On the other hand, if the liabilities exceed the assets, it may indicate that the company has more obligations than resources, which could be a sign of financial risk. Therefore, having equal-sized assets and liabilities provides a balanced and accurate representation of the company's financial standing. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.