Buy bilanzierung.eu ?
We are moving the project
bilanzierung.eu .
Are you interested in purchasing the domain
bilanzierung.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy bilanzierung.eu ?
What are transitory assets and/or liabilities?
Transitory assets and/or liabilities are items on a company's balance sheet that are expected to be settled or used up within a relatively short period of time, typically within one year. These items are considered to be temporary in nature and are not expected to have a long-term impact on the company's financial position. Examples of transitory assets include cash, accounts receivable, and inventory, while examples of transitory liabilities include accounts payable and short-term debt. It is important for investors and analysts to understand the nature of these transitory items when evaluating a company's financial health and performance. **
How are the assets and liabilities evaluated?
Assets and liabilities are evaluated based on their current market value or book value. For assets, this means determining their fair market value, which is the price that they could be sold for in the current market. Liabilities are evaluated based on their current outstanding balance or the amount that is owed. This evaluation helps to determine the financial health and position of a company, as well as its ability to meet its financial obligations. **
Similar search terms for Disorder
Top-Angebote
Products related to Disorder:
-
John Murray Anxiety: Practical About Panic: A Practical Guide to Understanding and Overcoming Anxiety DisorderDo you suffer from anxiety and panic? So did Joshua Fletcher, the author of the self-published bestseller ANXIETY: PANICKING ABOUT PANIC - but he treated his own condition successfully, went back to school, became a counsellor and emerged as one of the country's leading experts. ANXIETY: PRACTICAL ABOUT PANIC is a complete, easy to read and hugely practical book about anxiety from someone who knows how to recover and live your life to the full - and will show you how. Concentrating on the actions that you can take to alleviate and overcome your worries, this book is all about you and what you need to do to improve your life.8,99 £*Shipping: 2,99 £Secure redirect to the provider
-
New Harbinger Publications When Your Teen Has an Eating Disorder by Lauren Muhlheim & Laura Collins – Practical Recovery Guide & Mental Health Support CollectionIf your teen has an eating disorder-such as anorexia, bulimia, or binge eating-you may feel helpless, worried, or uncertain about how you can best support them. That's why you need real, proven-effective strategies you can use right away. Whether used in conjunction with treatment or on its own, this book offers an evidence-based approach you can use now to help your teen make healthy choices and stay well in body and mind.When Your Teen Has an Eating Disorder will empower you to help your teen using a unique, family-based treatment (FBT) approach. With this guide, you'll learn to respectfully and lovingly oversee your teen's nutritional rehabilitation, which includes helping to normalize eating behaviors, managing meals, expanding food flexibility, teaching independent and intuitive eating habits, and using coping strategies and recovery skills to prevent relapse.In addition to helping parents and caregivers, this book is a wonderful resource for mental health professionals, teachers, counselors, and coaches who work with parents of and teens with eating disorders. It clearly outlines the principles of FBT and the process of involving parents collaboratively in treatment.As a parent, feeding your child is a fundamental act of love-it has been from the start! However, when a child is affected by an eating disorder, parents often lose confidence in performing this basic task. This compassionate guide will help you gain the confidence needed to nurture your teen and help them heal.9,95 £*Shipping: 2,99 £Secure redirect to the provider
-
Quercus Financial Joy: Set your financial goals for 2026 - Banish Debt, Grow Your Money and Unlock Financial Freedom by Ken and Mary OkoroaforAs seen on ITV's This Morning! A life-changing 10-week plan to help you to turn your life around and design a path to financial freedom, enriched with the small experiences that bring you joy. Stop worrying about money. Start enjoying your life. You might be struggling in debt, living paycheque to paycheque, or worried about preparing for retirement; maybe you're considering your first investment, or you just want an escape plan from the '9 to 5'. Wherever you are on your journey, this book will revolutionize your lifestyle and your relationship with money. Authors Ken and Mary Okoroafor started out as resource-poor, working-class immigrants and have built a life of financial independence and joyful moments through hard work, smart saving and savvy investing. They know what it feels like to start from ground zero, and as a chartered accountant and former CFO, Ken shares his financial expertise to help you unlock the secret to building wealth. You'll learn how to take control of your finances, develop good money habits, become debt-free, invest in assets and multiply your income so you can create the freedom to travel, spend time with your loved ones and plan for a stress-free (early) retirement - all whilst prioritising your wellbeing and having fun! It also includes a dozen real-life interviews with singles, couples and those with children, from different backgrounds, age groups and stages of their money journey, including a few well-known public figures. Financial joy can be achieved by anyone - and it can start today, not tomorrow.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
HP 12c Platinum Financial Calculator (F2231AA)HP 12c Platinum Financial Calculator; Box includes Calculator, batteries, user manual, pouch. Display Description: 10 x 7-segment, single line. Built-in Functions: over 130. Character Display Maximum: 10. Entry System Logic: RPN; Algebraic. Graph Display Features: adjustable contrastA time-tested performer, the HP 12c has an easy-to-use layout, one-line LCD display and efficient RPN data entry. Easily calculate loan payments, interest rates and conversions, standard deviation, percent, TVM, NPV, IRR, cash flows, bonds and more. Over 120 built in functions.- Customizing Features.- Keystroke programming Memory capacity: 399 steps.- Time and Date Management.- Date arithmetic.- The Time-Tested Performer.- Business/Financial Features Statistical/Mathematical Features, Time and Date Management, and Customizing Features, Attractive one line x 10-character LCD display, Select business functions at your fingertips, Great mix of statistic, business and math functions, Read display results easily, even at an angle.- Business/Financial Features.- TVM (loans, savings, and leasing) Amortization Bond price and yield to maturity Cash flow analysis NPV, IRR Memory for up to 20 cash flows SL, DB, SOYD depreciation methods % change, % of total.- Statistical/Mathematical Features.- Cumulative statistical analysis Std. deviation, mean, weighted mean Linear regression Forecasting, correlation coefficient Total, £x, £x2, £y, £y2, £xy +, -, x, %, ÷, 1/x, ±, LN, ex, n!.- Ideal for.- Real estate, finance, accounting, economics and business work. Permitted for use on the CFP and CFA Certification Exams, and GARP FRM Exam.40,99 £*Shipping: 0,00 £Secure redirect to the provider


-
What is a statement of assets and liabilities?
A statement of assets and liabilities is a financial document that provides a snapshot of an individual's or organization's financial position at a specific point in time. It lists all the assets, such as cash, investments, property, and equipment, as well as all the liabilities, such as loans, mortgages, and other debts. The statement helps to assess the overall financial health and solvency of the entity by comparing the total assets to the total liabilities. It is an essential tool for financial planning, decision-making, and assessing the ability to meet financial obligations. **
-
What distinguishes bipolar disorder from borderline personality disorder?
Bipolar disorder is a mood disorder characterized by extreme mood swings between mania and depression, while borderline personality disorder is a personality disorder characterized by unstable relationships, self-image, and emotions. Bipolar disorder is primarily a mood disorder, while borderline personality disorder is a personality disorder that affects a person's overall sense of self and relationships. Additionally, bipolar disorder is typically episodic, with distinct periods of mania and depression, while borderline personality disorder is characterized by chronic patterns of instability. Treatment approaches for these disorders also differ, with bipolar disorder often treated with mood stabilizers and borderline personality disorder often treated with therapy focused on improving interpersonal relationships and emotional regulation. **
-
What differentiates bipolar disorder from borderline personality disorder?
Bipolar disorder is characterized by extreme mood swings between manic episodes (elevated mood, increased energy) and depressive episodes, while borderline personality disorder is characterized by unstable relationships, self-image, and emotions. Bipolar disorder is primarily a mood disorder, while borderline personality disorder is a personality disorder that affects a person's overall way of thinking, feeling, and behaving. Additionally, bipolar disorder is typically treated with mood stabilizers and other medications, while borderline personality disorder is often treated with therapy, such as dialectical behavior therapy. **
-
How can accounting, liabilities, and receivables be interconnected?
Accounting, liabilities, and receivables are interconnected in the sense that they all play a role in a company's financial health. Liabilities are debts or obligations that a company owes, which are recorded on the balance sheet as part of the accounting process. Receivables, on the other hand, represent money owed to the company by its customers or clients, and are also recorded on the balance sheet as assets. The relationship between these two is that receivables can eventually become liabilities if they are not collected in a timely manner, which can impact the company's financial position. Therefore, proper accounting practices are essential to accurately track and manage both liabilities and receivables to ensure the company's financial stability. **

Is it a brain disorder or an eye disorder?
It is an eye disorder. Amblyopia, also known as lazy eye, is a condition where one eye has reduced vision due to abnormal visual development in early childhood. It is not a brain disorder, but rather a problem with how the brain and eye work together to process visual information. Treatment for amblyopia typically involves correcting any underlying issues with the eye, such as using glasses or an eye patch to strengthen the weaker eye. **
When is a personality disorder considered a personality disorder?
A personality disorder is considered a personality disorder when it meets specific criteria outlined in the Diagnostic and Statistical Manual of Mental Disorders (DSM-5). These criteria include enduring patterns of behavior, cognition, and inner experience that deviate significantly from cultural expectations, are pervasive and inflexible, and lead to distress or impairment in social, occupational, or other areas of functioning. Additionally, the symptoms must be stable and of long duration, typically beginning in adolescence or early adulthood. A diagnosis of a personality disorder is made by a qualified mental health professional after a thorough assessment and evaluation of the individual's symptoms and history. **
Top-Angebote
Products related to Disorder:
-
Cambridge University Press Personality Disorder: From Evidence to UnderstandingPersonality disorder affects more than 10% of the population but is widely ignored by health professionals as it is viewed as a term of stigma. The new classification of personality disorder in the ICD-11 shows that we are all on a spectrum of personality disturbance and that this can change over time. This important new book explains why all health professionals need to be aware of personality disorders in their clinical practice. Abnormal personality, at all levels of severity, should be taken into account when choosing treatment, when predicting outcomes, when anticipating relapse, and when explaining diagnosis. Authored by leading experts in this field, this book explains how the new classification of personality disorders in the ICD-11 helps to select treatment programmes, plan long-term management and avoid adverse consequences in the treatment of this patient group29,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Riverhead Books Messy - The Power Of Disorder To Transform Our Lives by Tim HarfordMessy: The Power of Disorder to Transform Our Lives Description From the award-winning columnist and author of the national bestseller The Undercover Economist comes a provocative big idea book about the genuine benefits of being messy: at home; at work; in the classroom; and beyond. Look out for Tim's next book; Fifty Inventions That Shaped the Modern Economy. Messy: The Power of Disorder to Transform Our Lives celebrates the benefits that messiness has in our lives: why it's important; why we resist it; and why we should embrace it instead. Using research from neuroscience; psychology; social science; as well as captivating examples of real people doing extraordinary things; Tim Harford explains that the human qualities we value - creativity; responsiveness; resilience - are integral to the disorder; confusion; and disarray that produce them. From the music studio of Brian Eno to the Lincoln Memorial with Martin Luther King; Jr.; from the board room to the classroom; messiness lies at the core of how we innovate; how we achieve; how we reach each other - in short; how we succeed. In Messy; you'll learn about the unexpected connections between creativity and mess; understand why unexpected changes of plans; unfamiliar people; and unforeseen events can help generate new ideas and opportunities as they make you anxious and angry; and come to appreciate that the human inclination for tidiness - in our personal and professional lives; online; even in children's play - can mask deep and debilitating fragility that keep us from innovation. Stimulating and readable as it points exciting ways forward; Messy is an insightful exploration of the real advantages of mess in our lives.4,49 £*Shipping: 1,99 £Secure redirect to the provider
-
John Murray Anxiety: Practical About Panic: A Practical Guide to Understanding and Overcoming Anxiety DisorderDo you suffer from anxiety and panic? So did Joshua Fletcher, the author of the self-published bestseller ANXIETY: PANICKING ABOUT PANIC - but he treated his own condition successfully, went back to school, became a counsellor and emerged as one of the country's leading experts. ANXIETY: PRACTICAL ABOUT PANIC is a complete, easy to read and hugely practical book about anxiety from someone who knows how to recover and live your life to the full - and will show you how. Concentrating on the actions that you can take to alleviate and overcome your worries, this book is all about you and what you need to do to improve your life.8,99 £*Shipping: 2,99 £Secure redirect to the provider
-
New Harbinger Publications When Your Teen Has an Eating Disorder by Lauren Muhlheim & Laura Collins – Practical Recovery Guide & Mental Health Support CollectionIf your teen has an eating disorder-such as anorexia, bulimia, or binge eating-you may feel helpless, worried, or uncertain about how you can best support them. That's why you need real, proven-effective strategies you can use right away. Whether used in conjunction with treatment or on its own, this book offers an evidence-based approach you can use now to help your teen make healthy choices and stay well in body and mind.When Your Teen Has an Eating Disorder will empower you to help your teen using a unique, family-based treatment (FBT) approach. With this guide, you'll learn to respectfully and lovingly oversee your teen's nutritional rehabilitation, which includes helping to normalize eating behaviors, managing meals, expanding food flexibility, teaching independent and intuitive eating habits, and using coping strategies and recovery skills to prevent relapse.In addition to helping parents and caregivers, this book is a wonderful resource for mental health professionals, teachers, counselors, and coaches who work with parents of and teens with eating disorders. It clearly outlines the principles of FBT and the process of involving parents collaboratively in treatment.As a parent, feeding your child is a fundamental act of love-it has been from the start! However, when a child is affected by an eating disorder, parents often lose confidence in performing this basic task. This compassionate guide will help you gain the confidence needed to nurture your teen and help them heal.9,95 £*Shipping: 2,99 £Secure redirect to the provider
-
What are transitory assets and/or liabilities?
Transitory assets and/or liabilities are items on a company's balance sheet that are expected to be settled or used up within a relatively short period of time, typically within one year. These items are considered to be temporary in nature and are not expected to have a long-term impact on the company's financial position. Examples of transitory assets include cash, accounts receivable, and inventory, while examples of transitory liabilities include accounts payable and short-term debt. It is important for investors and analysts to understand the nature of these transitory items when evaluating a company's financial health and performance. **
-
How are the assets and liabilities evaluated?
Assets and liabilities are evaluated based on their current market value or book value. For assets, this means determining their fair market value, which is the price that they could be sold for in the current market. Liabilities are evaluated based on their current outstanding balance or the amount that is owed. This evaluation helps to determine the financial health and position of a company, as well as its ability to meet its financial obligations. **
-
What is a statement of assets and liabilities?
A statement of assets and liabilities is a financial document that provides a snapshot of an individual's or organization's financial position at a specific point in time. It lists all the assets, such as cash, investments, property, and equipment, as well as all the liabilities, such as loans, mortgages, and other debts. The statement helps to assess the overall financial health and solvency of the entity by comparing the total assets to the total liabilities. It is an essential tool for financial planning, decision-making, and assessing the ability to meet financial obligations. **
-
What distinguishes bipolar disorder from borderline personality disorder?
Bipolar disorder is a mood disorder characterized by extreme mood swings between mania and depression, while borderline personality disorder is a personality disorder characterized by unstable relationships, self-image, and emotions. Bipolar disorder is primarily a mood disorder, while borderline personality disorder is a personality disorder that affects a person's overall sense of self and relationships. Additionally, bipolar disorder is typically episodic, with distinct periods of mania and depression, while borderline personality disorder is characterized by chronic patterns of instability. Treatment approaches for these disorders also differ, with bipolar disorder often treated with mood stabilizers and borderline personality disorder often treated with therapy focused on improving interpersonal relationships and emotional regulation. **
Similar search terms for Disorder
-
Quercus Financial Joy: Set your financial goals for 2026 - Banish Debt, Grow Your Money and Unlock Financial Freedom by Ken and Mary OkoroaforAs seen on ITV's This Morning! A life-changing 10-week plan to help you to turn your life around and design a path to financial freedom, enriched with the small experiences that bring you joy. Stop worrying about money. Start enjoying your life. You might be struggling in debt, living paycheque to paycheque, or worried about preparing for retirement; maybe you're considering your first investment, or you just want an escape plan from the '9 to 5'. Wherever you are on your journey, this book will revolutionize your lifestyle and your relationship with money. Authors Ken and Mary Okoroafor started out as resource-poor, working-class immigrants and have built a life of financial independence and joyful moments through hard work, smart saving and savvy investing. They know what it feels like to start from ground zero, and as a chartered accountant and former CFO, Ken shares his financial expertise to help you unlock the secret to building wealth. You'll learn how to take control of your finances, develop good money habits, become debt-free, invest in assets and multiply your income so you can create the freedom to travel, spend time with your loved ones and plan for a stress-free (early) retirement - all whilst prioritising your wellbeing and having fun! It also includes a dozen real-life interviews with singles, couples and those with children, from different backgrounds, age groups and stages of their money journey, including a few well-known public figures. Financial joy can be achieved by anyone - and it can start today, not tomorrow.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
HP 12c Platinum Financial Calculator (F2231AA)HP 12c Platinum Financial Calculator; Box includes Calculator, batteries, user manual, pouch. Display Description: 10 x 7-segment, single line. Built-in Functions: over 130. Character Display Maximum: 10. Entry System Logic: RPN; Algebraic. Graph Display Features: adjustable contrastA time-tested performer, the HP 12c has an easy-to-use layout, one-line LCD display and efficient RPN data entry. Easily calculate loan payments, interest rates and conversions, standard deviation, percent, TVM, NPV, IRR, cash flows, bonds and more. Over 120 built in functions.- Customizing Features.- Keystroke programming Memory capacity: 399 steps.- Time and Date Management.- Date arithmetic.- The Time-Tested Performer.- Business/Financial Features Statistical/Mathematical Features, Time and Date Management, and Customizing Features, Attractive one line x 10-character LCD display, Select business functions at your fingertips, Great mix of statistic, business and math functions, Read display results easily, even at an angle.- Business/Financial Features.- TVM (loans, savings, and leasing) Amortization Bond price and yield to maturity Cash flow analysis NPV, IRR Memory for up to 20 cash flows SL, DB, SOYD depreciation methods % change, % of total.- Statistical/Mathematical Features.- Cumulative statistical analysis Std. deviation, mean, weighted mean Linear regression Forecasting, correlation coefficient Total, £x, £x2, £y, £y2, £xy +, -, x, %, ÷, 1/x, ±, LN, ex, n!.- Ideal for.- Real estate, finance, accounting, economics and business work. Permitted for use on the CFP and CFA Certification Exams, and GARP FRM Exam.40,99 £*Shipping: 0,00 £Secure redirect to the provider
-
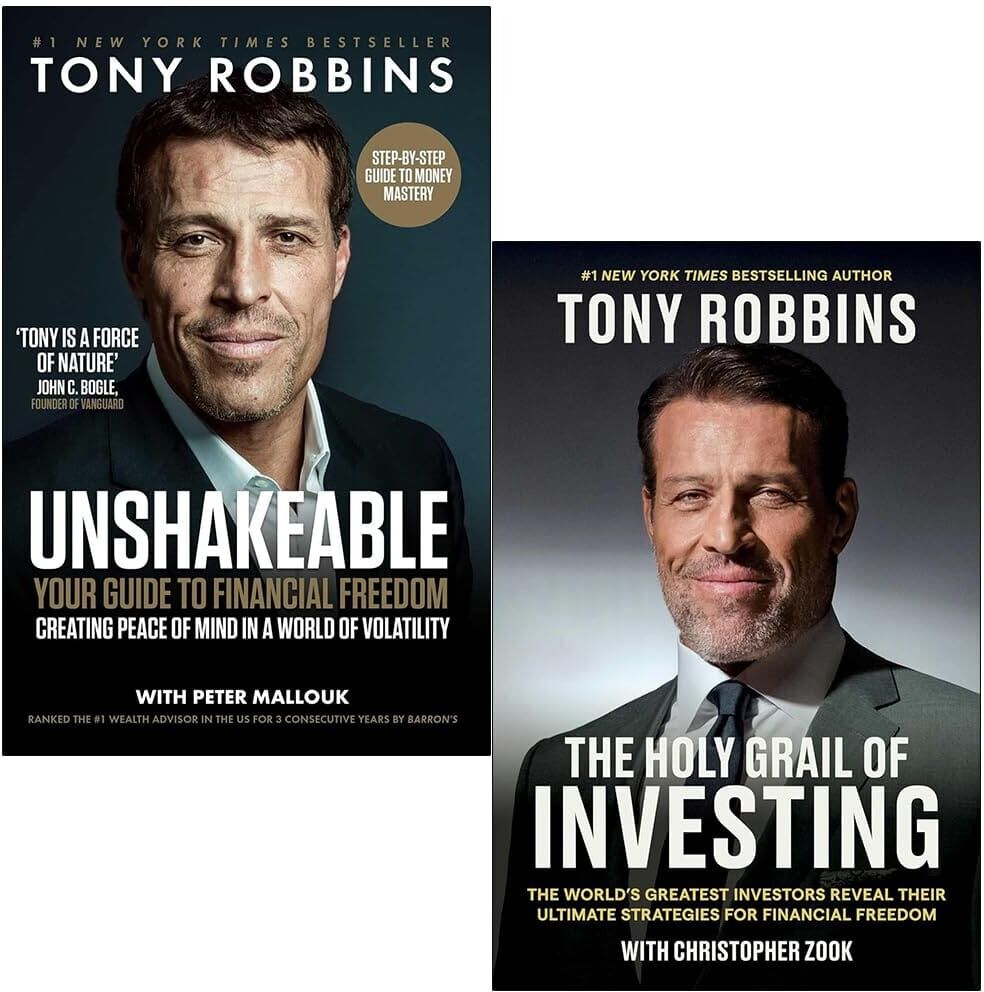
Financial Freedom Collection By Tony Robbins 2 Books Set - Non Fiction - Paperback Simon & SchusterTitles in this set: 1. Unshakeable: Your Guide to Financial Freedom 2. The Holy Grail of Investing Description: Unshakeable: Your Guide to Financial Freedom Tony Robbins, arguably the most recognizable life and business strategist and guru, is back with a timely, unique follow-up. Market corrections are as constant as seasons are in nature. There have been 30 such corrections in the past 30 years, yet there’s never been an action plan for how not only to survive, but thrive through each change in the stock market. Building upon the principles in Money: Master the Game, Robbins offers the reader specific steps they can implement to protect their investments while maximizing their wealth. It’s a detailed guide designed for investors, articulated in the common-sense, practical manner that the millions of loyal Robbins fans and students have come to expect and rely upon. Few have navigated the turbulence of the stock market as adeptly and successfully as Tony Robbins. His proven, consistent success over decades makes him singularly qualified to help investors (both seasoned and first-timers alike) preserve and add to their investments. The Holy Grail of Investing In this new book, Tony Robbins teams up with Christopher Zook, a renowned financial investor . Together they reveal how, for decades, trillions of dollars of smart money – think of large institutions, sovereign wealth funds, individuals with ultra-high-net worth – have been making outsized returns using alternative investments in private equity, private credit, private real estate, energy and venture capital. Until recently, the vast majority of investors – those of us without insider access or eye-popping checkbooks – have been locked out of these exciting, high-yield opportunities. But there is a change underway. Alternative investments are coming to the masses, and investors need to know how to navigate their options, assess the merits of these opportunities, and determine how to best take advantage of this massive trend. In The Holy Grain of Investing , you’ll discover: Where opportunities will arise as we transition from the 'free money' era of zero interest rates to a new more realistic environment. How to take advantage of the trillions flowing into private investments by owning a piece of the firms that manage the assets. How to take advantage of private credit as an alternative (or compliment) to bonds. How and why professional sports teams have become an asset class of their own. How the renewable energy revolution will create new winners and losers. How investments in private real estate can work as an inflationary hedge. Interviews, advice, and insights from some of the world’s most formidable titans of industry, such as Howard Marks of OakTree Capital, Vinod Khosla of Khosla Capital, Barry Sternlicht of Starwood, Robert Smith of Vista, and Peter Theil of Founders Fund, among others. The market is changing, and the conventional wisdom no longer applies. Are you ready to add some...18,99 £*Shipping: 2,99 £Secure redirect to the provider
-
What differentiates bipolar disorder from borderline personality disorder?
Bipolar disorder is characterized by extreme mood swings between manic episodes (elevated mood, increased energy) and depressive episodes, while borderline personality disorder is characterized by unstable relationships, self-image, and emotions. Bipolar disorder is primarily a mood disorder, while borderline personality disorder is a personality disorder that affects a person's overall way of thinking, feeling, and behaving. Additionally, bipolar disorder is typically treated with mood stabilizers and other medications, while borderline personality disorder is often treated with therapy, such as dialectical behavior therapy. **
-
How can accounting, liabilities, and receivables be interconnected?
Accounting, liabilities, and receivables are interconnected in the sense that they all play a role in a company's financial health. Liabilities are debts or obligations that a company owes, which are recorded on the balance sheet as part of the accounting process. Receivables, on the other hand, represent money owed to the company by its customers or clients, and are also recorded on the balance sheet as assets. The relationship between these two is that receivables can eventually become liabilities if they are not collected in a timely manner, which can impact the company's financial position. Therefore, proper accounting practices are essential to accurately track and manage both liabilities and receivables to ensure the company's financial stability. **
-
Is it a brain disorder or an eye disorder?
It is an eye disorder. Amblyopia, also known as lazy eye, is a condition where one eye has reduced vision due to abnormal visual development in early childhood. It is not a brain disorder, but rather a problem with how the brain and eye work together to process visual information. Treatment for amblyopia typically involves correcting any underlying issues with the eye, such as using glasses or an eye patch to strengthen the weaker eye. **
-
When is a personality disorder considered a personality disorder?
A personality disorder is considered a personality disorder when it meets specific criteria outlined in the Diagnostic and Statistical Manual of Mental Disorders (DSM-5). These criteria include enduring patterns of behavior, cognition, and inner experience that deviate significantly from cultural expectations, are pervasive and inflexible, and lead to distress or impairment in social, occupational, or other areas of functioning. Additionally, the symptoms must be stable and of long duration, typically beginning in adolescence or early adulthood. A diagnosis of a personality disorder is made by a qualified mental health professional after a thorough assessment and evaluation of the individual's symptoms and history. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.