Buy bilanzierung.eu ?
We are moving the project
bilanzierung.eu .
Are you interested in purchasing the domain
bilanzierung.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy bilanzierung.eu ?
What are transitory assets and/or liabilities?
Transitory assets and/or liabilities are items on a company's balance sheet that are expected to be settled or used up within a relatively short period of time, typically within one year. These items are considered to be temporary in nature and are not expected to have a long-term impact on the company's financial position. Examples of transitory assets include cash, accounts receivable, and inventory, while examples of transitory liabilities include accounts payable and short-term debt. It is important for investors and analysts to understand the nature of these transitory items when evaluating a company's financial health and performance. **
How are the assets and liabilities evaluated?
Assets and liabilities are evaluated based on their current market value or book value. For assets, this means determining their fair market value, which is the price that they could be sold for in the current market. Liabilities are evaluated based on their current outstanding balance or the amount that is owed. This evaluation helps to determine the financial health and position of a company, as well as its ability to meet its financial obligations. **
Similar search terms for Appropriate
Top-Angebote
Products related to Appropriate:
-
Quercus Financial Joy: Set your financial goals for 2026 - Banish Debt, Grow Your Money and Unlock Financial Freedom by Ken and Mary OkoroaforAs seen on ITV's This Morning! A life-changing 10-week plan to help you to turn your life around and design a path to financial freedom, enriched with the small experiences that bring you joy. Stop worrying about money. Start enjoying your life. You might be struggling in debt, living paycheque to paycheque, or worried about preparing for retirement; maybe you're considering your first investment, or you just want an escape plan from the '9 to 5'. Wherever you are on your journey, this book will revolutionize your lifestyle and your relationship with money. Authors Ken and Mary Okoroafor started out as resource-poor, working-class immigrants and have built a life of financial independence and joyful moments through hard work, smart saving and savvy investing. They know what it feels like to start from ground zero, and as a chartered accountant and former CFO, Ken shares his financial expertise to help you unlock the secret to building wealth. You'll learn how to take control of your finances, develop good money habits, become debt-free, invest in assets and multiply your income so you can create the freedom to travel, spend time with your loved ones and plan for a stress-free (early) retirement - all whilst prioritising your wellbeing and having fun! It also includes a dozen real-life interviews with singles, couples and those with children, from different backgrounds, age groups and stages of their money journey, including a few well-known public figures. Financial joy can be achieved by anyone - and it can start today, not tomorrow.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
HP 12c Platinum Financial Calculator (F2231AA)HP 12c Platinum Financial Calculator; Box includes Calculator, batteries, user manual, pouch. Display Description: 10 x 7-segment, single line. Built-in Functions: over 130. Character Display Maximum: 10. Entry System Logic: RPN; Algebraic. Graph Display Features: adjustable contrastA time-tested performer, the HP 12c has an easy-to-use layout, one-line LCD display and efficient RPN data entry. Easily calculate loan payments, interest rates and conversions, standard deviation, percent, TVM, NPV, IRR, cash flows, bonds and more. Over 120 built in functions.- Customizing Features.- Keystroke programming Memory capacity: 399 steps.- Time and Date Management.- Date arithmetic.- The Time-Tested Performer.- Business/Financial Features Statistical/Mathematical Features, Time and Date Management, and Customizing Features, Attractive one line x 10-character LCD display, Select business functions at your fingertips, Great mix of statistic, business and math functions, Read display results easily, even at an angle.- Business/Financial Features.- TVM (loans, savings, and leasing) Amortization Bond price and yield to maturity Cash flow analysis NPV, IRR Memory for up to 20 cash flows SL, DB, SOYD depreciation methods % change, % of total.- Statistical/Mathematical Features.- Cumulative statistical analysis Std. deviation, mean, weighted mean Linear regression Forecasting, correlation coefficient Total, £x, £x2, £y, £y2, £xy +, -, x, %, ÷, 1/x, ±, LN, ex, n!.- Ideal for.- Real estate, finance, accounting, economics and business work. Permitted for use on the CFP and CFA Certification Exams, and GARP FRM Exam.40,99 £*Shipping: 0,00 £Secure redirect to the provider
-
Financial Freedom Collection By Tony Robbins 2 Books Set - Non Fiction - Paperback Simon & SchusterTitles in this set: 1. Unshakeable: Your Guide to Financial Freedom 2. The Holy Grail of Investing Description: Unshakeable: Your Guide to Financial Freedom Tony Robbins, arguably the most recognizable life and business strategist and guru, is back with a timely, unique follow-up. Market corrections are as constant as seasons are in nature. There have been 30 such corrections in the past 30 years, yet there’s never been an action plan for how not only to survive, but thrive through each change in the stock market. Building upon the principles in Money: Master the Game, Robbins offers the reader specific steps they can implement to protect their investments while maximizing their wealth. It’s a detailed guide designed for investors, articulated in the common-sense, practical manner that the millions of loyal Robbins fans and students have come to expect and rely upon. Few have navigated the turbulence of the stock market as adeptly and successfully as Tony Robbins. His proven, consistent success over decades makes him singularly qualified to help investors (both seasoned and first-timers alike) preserve and add to their investments. The Holy Grail of Investing In this new book, Tony Robbins teams up with Christopher Zook, a renowned financial investor . Together they reveal how, for decades, trillions of dollars of smart money – think of large institutions, sovereign wealth funds, individuals with ultra-high-net worth – have been making outsized returns using alternative investments in private equity, private credit, private real estate, energy and venture capital. Until recently, the vast majority of investors – those of us without insider access or eye-popping checkbooks – have been locked out of these exciting, high-yield opportunities. But there is a change underway. Alternative investments are coming to the masses, and investors need to know how to navigate their options, assess the merits of these opportunities, and determine how to best take advantage of this massive trend. In The Holy Grain of Investing , you’ll discover: Where opportunities will arise as we transition from the 'free money' era of zero interest rates to a new more realistic environment. How to take advantage of the trillions flowing into private investments by owning a piece of the firms that manage the assets. How to take advantage of private credit as an alternative (or compliment) to bonds. How and why professional sports teams have become an asset class of their own. How the renewable energy revolution will create new winners and losers. How investments in private real estate can work as an inflationary hedge. Interviews, advice, and insights from some of the world’s most formidable titans of industry, such as Howard Marks of OakTree Capital, Vinod Khosla of Khosla Capital, Barry Sternlicht of Starwood, Robert Smith of Vista, and Peter Theil of Founders Fund, among others. The market is changing, and the conventional wisdom no longer applies. Are you ready to add some...18,99 £*Shipping: 2,99 £Secure redirect to the provider


-
What is a statement of assets and liabilities?
A statement of assets and liabilities is a financial document that provides a snapshot of an individual's or organization's financial position at a specific point in time. It lists all the assets, such as cash, investments, property, and equipment, as well as all the liabilities, such as loans, mortgages, and other debts. The statement helps to assess the overall financial health and solvency of the entity by comparing the total assets to the total liabilities. It is an essential tool for financial planning, decision-making, and assessing the ability to meet financial obligations. **
-
How can accounting, liabilities, and receivables be interconnected?
Accounting, liabilities, and receivables are interconnected in the sense that they all play a role in a company's financial health. Liabilities are debts or obligations that a company owes, which are recorded on the balance sheet as part of the accounting process. Receivables, on the other hand, represent money owed to the company by its customers or clients, and are also recorded on the balance sheet as assets. The relationship between these two is that receivables can eventually become liabilities if they are not collected in a timely manner, which can impact the company's financial position. Therefore, proper accounting practices are essential to accurately track and manage both liabilities and receivables to ensure the company's financial stability. **
-
Why must the assets and liabilities be equal in size?
The assets and liabilities must be equal in size because they represent the financial position of a company at a specific point in time. If the assets exceed the liabilities, it may indicate that the company has more resources than it owes, which could be a positive sign of financial health. On the other hand, if the liabilities exceed the assets, it may indicate that the company has more obligations than resources, which could be a sign of financial risk. Therefore, having equal-sized assets and liabilities provides a balanced and accurate representation of the company's financial standing. **
-
How much board money is appropriate with an income of 390?
With an income of 390, it is recommended to allocate around 25-30% of your income towards board money. This would amount to approximately 97.50 to 117 per month. It is important to consider your other expenses and financial goals when determining how much to allocate towards board money. **
How much board money is appropriate for an income of 390?
For an income of 390, a reasonable amount of board money would be around 100-150. This would allow for a fair contribution to household expenses while still leaving enough for personal savings and discretionary spending. It's important to consider the cost of living in the specific area and the individual's financial goals when determining the appropriate amount of board money. **
What are bank liabilities and bank balances in accounting?
In accounting, bank liabilities refer to the obligations that a bank owes to its customers and other financial institutions. This includes deposits made by customers, such as savings accounts, checking accounts, and certificates of deposit. Bank balances, on the other hand, represent the amount of money that a bank holds in its accounts, including cash reserves and funds deposited with other banks. These balances are crucial for a bank's liquidity and ability to meet its financial obligations. **
Top-Angebote
Products related to Appropriate:
-
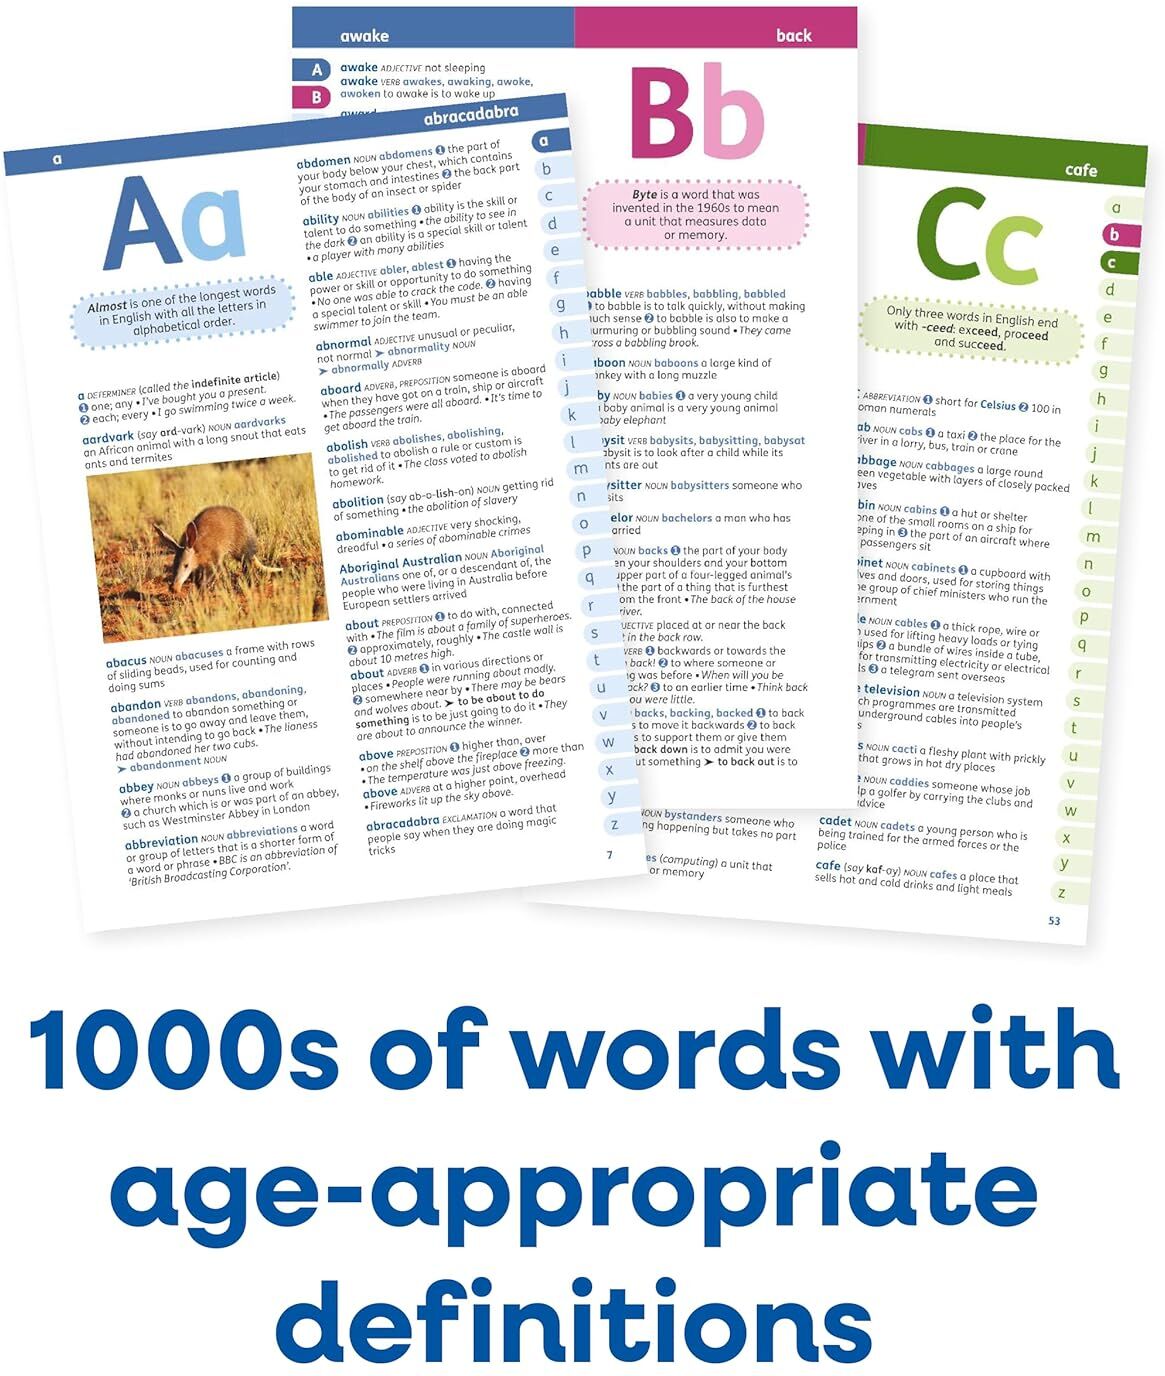
OUP Oxford Oxford Children's Thesaurus: Build vocabulary skills for ages 8+ with age-appropriate synonyms (Oxford Children's Dictionaries)Help children take their writing and speaking skills to the next level with the Oxford Children's Thesaurus - the essential vocabulary builder for young learners aged 8+. Perfect for home learning, homework support, or independent writing, this thesaurus inspires children to expand their language with thousands of exciting, creative, age-appropriate synonyms. Key features include: • Builds confident writing and speaking skills for ages 8+ (KS2), with thousands of exciting, creative synonyms designed specifically for children. • Clear, age-appropriate example sentences show synonyms in context, making it easy for young learners to understand and use new vocabulary independently. • Photographic images throughout help support comprehension and strengthen visual learning. • Easy-to-navigate design with alphabet thumb tabs, allowing children to quickly find the words they need for homework, school projects, or creative writing. • Includes a full writing supplement covering fiction, non-fiction, reports, and descriptive writing, helping children apply their new vocabulary in real tasks. • Overused Word panels offer smarter, more interesting alternatives to words like nice, good, big, and fun, helping children avoid repetition. • Writing Tips panels inspire creativity and help children experiment with tone, detail, and expression. • Word Web panels show related words and ideas to further develop vocabulary breadth and help children make richer word choices. • Powered by the Oxford Children's Corpus - a unique database of children's writing - ensuring vocabulary reflects real writing by real children and supports the words young learners actually use. • An ideal companion to the Oxford Children's Dictionary (9781382074117), supporting both vocabulary building and dictionary skills.7,99 £*Shipping: 2,99 £Secure redirect to the provider
-
OUP Oxford Oxford Children's Dictionary: For ages 8+ with age-appropriate definitions and full-colour images (Oxford Children's Dictionaries)The Oxford Children's Dictionary is the ideal English language reference book for children aged 8+, supporting vocabulary growth, spelling accuracy, and reading comprehension at home or for homework. Fully updated with new words, age-appropriate definitions, and clear example sentences, this accessible dictionary helps young learners understand and use language with confidence. Key features include: • Perfect for children aged 8+ and at Key Stage 2 (KS2), supporting vocabulary development, spelling confidence, and reading comprehension for schoolwork, homework, and independent learning. • Features new and updated words with clear example sentences, helping children understand meaning, spelling, and usage in context. • Clear, age-appropriate definitions carefully levelled for young readers, enabling children to look up words independently and accurately. • Created using the Oxford Children's Corpus - a unique database of children's writing - ensuring the vocabulary reflects real language used by children and supports modern English learning. • Full-colour design with photographic images to aid understanding and make the dictionary more engaging and visually accessible. • Alphabet thumb tabs for quick and easy navigation, helping children confidently find the words they need. • Includes a helpful support section on spelling, punctuation, and grammar, reinforcing key English skills taught at primary level. • An ideal companion to the Oxford Children's Thesaurus (9781382074131), helping children improve both word choice and writing quality.7,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Quercus Financial Joy: Set your financial goals for 2026 - Banish Debt, Grow Your Money and Unlock Financial Freedom by Ken and Mary OkoroaforAs seen on ITV's This Morning! A life-changing 10-week plan to help you to turn your life around and design a path to financial freedom, enriched with the small experiences that bring you joy. Stop worrying about money. Start enjoying your life. You might be struggling in debt, living paycheque to paycheque, or worried about preparing for retirement; maybe you're considering your first investment, or you just want an escape plan from the '9 to 5'. Wherever you are on your journey, this book will revolutionize your lifestyle and your relationship with money. Authors Ken and Mary Okoroafor started out as resource-poor, working-class immigrants and have built a life of financial independence and joyful moments through hard work, smart saving and savvy investing. They know what it feels like to start from ground zero, and as a chartered accountant and former CFO, Ken shares his financial expertise to help you unlock the secret to building wealth. You'll learn how to take control of your finances, develop good money habits, become debt-free, invest in assets and multiply your income so you can create the freedom to travel, spend time with your loved ones and plan for a stress-free (early) retirement - all whilst prioritising your wellbeing and having fun! It also includes a dozen real-life interviews with singles, couples and those with children, from different backgrounds, age groups and stages of their money journey, including a few well-known public figures. Financial joy can be achieved by anyone - and it can start today, not tomorrow.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
HP 12c Platinum Financial Calculator (F2231AA)HP 12c Platinum Financial Calculator; Box includes Calculator, batteries, user manual, pouch. Display Description: 10 x 7-segment, single line. Built-in Functions: over 130. Character Display Maximum: 10. Entry System Logic: RPN; Algebraic. Graph Display Features: adjustable contrastA time-tested performer, the HP 12c has an easy-to-use layout, one-line LCD display and efficient RPN data entry. Easily calculate loan payments, interest rates and conversions, standard deviation, percent, TVM, NPV, IRR, cash flows, bonds and more. Over 120 built in functions.- Customizing Features.- Keystroke programming Memory capacity: 399 steps.- Time and Date Management.- Date arithmetic.- The Time-Tested Performer.- Business/Financial Features Statistical/Mathematical Features, Time and Date Management, and Customizing Features, Attractive one line x 10-character LCD display, Select business functions at your fingertips, Great mix of statistic, business and math functions, Read display results easily, even at an angle.- Business/Financial Features.- TVM (loans, savings, and leasing) Amortization Bond price and yield to maturity Cash flow analysis NPV, IRR Memory for up to 20 cash flows SL, DB, SOYD depreciation methods % change, % of total.- Statistical/Mathematical Features.- Cumulative statistical analysis Std. deviation, mean, weighted mean Linear regression Forecasting, correlation coefficient Total, £x, £x2, £y, £y2, £xy +, -, x, %, ÷, 1/x, ±, LN, ex, n!.- Ideal for.- Real estate, finance, accounting, economics and business work. Permitted for use on the CFP and CFA Certification Exams, and GARP FRM Exam.40,99 £*Shipping: 0,00 £Secure redirect to the provider
-
What are transitory assets and/or liabilities?
Transitory assets and/or liabilities are items on a company's balance sheet that are expected to be settled or used up within a relatively short period of time, typically within one year. These items are considered to be temporary in nature and are not expected to have a long-term impact on the company's financial position. Examples of transitory assets include cash, accounts receivable, and inventory, while examples of transitory liabilities include accounts payable and short-term debt. It is important for investors and analysts to understand the nature of these transitory items when evaluating a company's financial health and performance. **
-
How are the assets and liabilities evaluated?
Assets and liabilities are evaluated based on their current market value or book value. For assets, this means determining their fair market value, which is the price that they could be sold for in the current market. Liabilities are evaluated based on their current outstanding balance or the amount that is owed. This evaluation helps to determine the financial health and position of a company, as well as its ability to meet its financial obligations. **
-
What is a statement of assets and liabilities?
A statement of assets and liabilities is a financial document that provides a snapshot of an individual's or organization's financial position at a specific point in time. It lists all the assets, such as cash, investments, property, and equipment, as well as all the liabilities, such as loans, mortgages, and other debts. The statement helps to assess the overall financial health and solvency of the entity by comparing the total assets to the total liabilities. It is an essential tool for financial planning, decision-making, and assessing the ability to meet financial obligations. **
-
How can accounting, liabilities, and receivables be interconnected?
Accounting, liabilities, and receivables are interconnected in the sense that they all play a role in a company's financial health. Liabilities are debts or obligations that a company owes, which are recorded on the balance sheet as part of the accounting process. Receivables, on the other hand, represent money owed to the company by its customers or clients, and are also recorded on the balance sheet as assets. The relationship between these two is that receivables can eventually become liabilities if they are not collected in a timely manner, which can impact the company's financial position. Therefore, proper accounting practices are essential to accurately track and manage both liabilities and receivables to ensure the company's financial stability. **
Similar search terms for Appropriate
-
Financial Freedom Collection By Tony Robbins 2 Books Set - Non Fiction - Paperback Simon & SchusterTitles in this set: 1. Unshakeable: Your Guide to Financial Freedom 2. The Holy Grail of Investing Description: Unshakeable: Your Guide to Financial Freedom Tony Robbins, arguably the most recognizable life and business strategist and guru, is back with a timely, unique follow-up. Market corrections are as constant as seasons are in nature. There have been 30 such corrections in the past 30 years, yet there’s never been an action plan for how not only to survive, but thrive through each change in the stock market. Building upon the principles in Money: Master the Game, Robbins offers the reader specific steps they can implement to protect their investments while maximizing their wealth. It’s a detailed guide designed for investors, articulated in the common-sense, practical manner that the millions of loyal Robbins fans and students have come to expect and rely upon. Few have navigated the turbulence of the stock market as adeptly and successfully as Tony Robbins. His proven, consistent success over decades makes him singularly qualified to help investors (both seasoned and first-timers alike) preserve and add to their investments. The Holy Grail of Investing In this new book, Tony Robbins teams up with Christopher Zook, a renowned financial investor . Together they reveal how, for decades, trillions of dollars of smart money – think of large institutions, sovereign wealth funds, individuals with ultra-high-net worth – have been making outsized returns using alternative investments in private equity, private credit, private real estate, energy and venture capital. Until recently, the vast majority of investors – those of us without insider access or eye-popping checkbooks – have been locked out of these exciting, high-yield opportunities. But there is a change underway. Alternative investments are coming to the masses, and investors need to know how to navigate their options, assess the merits of these opportunities, and determine how to best take advantage of this massive trend. In The Holy Grain of Investing , you’ll discover: Where opportunities will arise as we transition from the 'free money' era of zero interest rates to a new more realistic environment. How to take advantage of the trillions flowing into private investments by owning a piece of the firms that manage the assets. How to take advantage of private credit as an alternative (or compliment) to bonds. How and why professional sports teams have become an asset class of their own. How the renewable energy revolution will create new winners and losers. How investments in private real estate can work as an inflationary hedge. Interviews, advice, and insights from some of the world’s most formidable titans of industry, such as Howard Marks of OakTree Capital, Vinod Khosla of Khosla Capital, Barry Sternlicht of Starwood, Robert Smith of Vista, and Peter Theil of Founders Fund, among others. The market is changing, and the conventional wisdom no longer applies. Are you ready to add some...18,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing FAKE: Fake Money, Fake Teachers, Fake Assets & Rich Dad Poor Dad By Robert T. Kiyosaki 2 Books Collection SetFAKE: Fake Money, Fake Teachers, Fake Assets & Rich Dad Poor Dad By Robert T. Kiyosaki 2 Books Collection Set: FAKE: Fake Money, Fake Teachers, Fake Assets: In FAKE: Fake Money, Fake Teachers, Fake Assets, Robert delivers insights and answers that help ordinary people―who probably haven’t had a lot of financial education―determine what’s ‘real’ and relevant to their financial lives. Every day we are bombarded with news reports and information and opinions… How do we decipher fact from fiction? How do we differentiate between truth and lies? And determine what’s real… from what isn’t? Kiyosaki believes that it starts with education, financial education designed to make us smarter with our money―and able to fight what’s fake and use what isn’t to secure our financial future. Rich Dad Poor Dad: Rich Dad Poor Dad is Robert's story of growing up with two dads — his real father and the father of his best friend, his rich dad — and the ways in which both men shaped his thoughts about money and investing. The book explodes the myth that you need to earn a high income to be rich and explains the difference between working for money and having your money work for you.12,95 £*Shipping: 2,99 £Secure redirect to the provider
-
Scribe UK Billion Dollar Whale by Tom Wright & Bradley Hope – Financial Fraud True Crime BestsellerThe epic story of how a young social climber from Malaysia pulled off one of the biggest financial heists in history. In 2015, rumours began circulating that billions of dollars had been stolen from a Malaysian investment fund. The mastermind of the heist was twenty-seven-year-old Jho Low, a serial fabulist from an upper-middle-class Malaysian family, who had carefully built his reputation as a member of the jet-setting elite by arranging and financing elaborate parties for Wall Street bankers, celebrities, and even royalty. With the aid of Goldman Sachs and others, Low stole billions of dollars, right under the nose of global financial industry watchdogs. He used the money to finance elections, purchase luxury real estate, throw champagne-drenched parties, and bankroll Hollywood films like The Wolf of Wall Street. Billion Dollar Whale reveals how this silver-tongued con man, a ‘modern Gatsby’, emerged from obscurity to pull off one of the most audacious financial heists the world has ever seen, and how the financial industry let him. It is a classic harrowing parable of hubris and greed in the financial world.4,95 £*Shipping: 1,99 £Secure redirect to the provider
-
Why must the assets and liabilities be equal in size?
The assets and liabilities must be equal in size because they represent the financial position of a company at a specific point in time. If the assets exceed the liabilities, it may indicate that the company has more resources than it owes, which could be a positive sign of financial health. On the other hand, if the liabilities exceed the assets, it may indicate that the company has more obligations than resources, which could be a sign of financial risk. Therefore, having equal-sized assets and liabilities provides a balanced and accurate representation of the company's financial standing. **
-
How much board money is appropriate with an income of 390?
With an income of 390, it is recommended to allocate around 25-30% of your income towards board money. This would amount to approximately 97.50 to 117 per month. It is important to consider your other expenses and financial goals when determining how much to allocate towards board money. **
-
How much board money is appropriate for an income of 390?
For an income of 390, a reasonable amount of board money would be around 100-150. This would allow for a fair contribution to household expenses while still leaving enough for personal savings and discretionary spending. It's important to consider the cost of living in the specific area and the individual's financial goals when determining the appropriate amount of board money. **
-
What are bank liabilities and bank balances in accounting?
In accounting, bank liabilities refer to the obligations that a bank owes to its customers and other financial institutions. This includes deposits made by customers, such as savings accounts, checking accounts, and certificates of deposit. Bank balances, on the other hand, represent the amount of money that a bank holds in its accounts, including cash reserves and funds deposited with other banks. These balances are crucial for a bank's liquidity and ability to meet its financial obligations. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.